Founders

How to Build an Advisor Bench for a One-Person Company

Antonio Evans9 min read

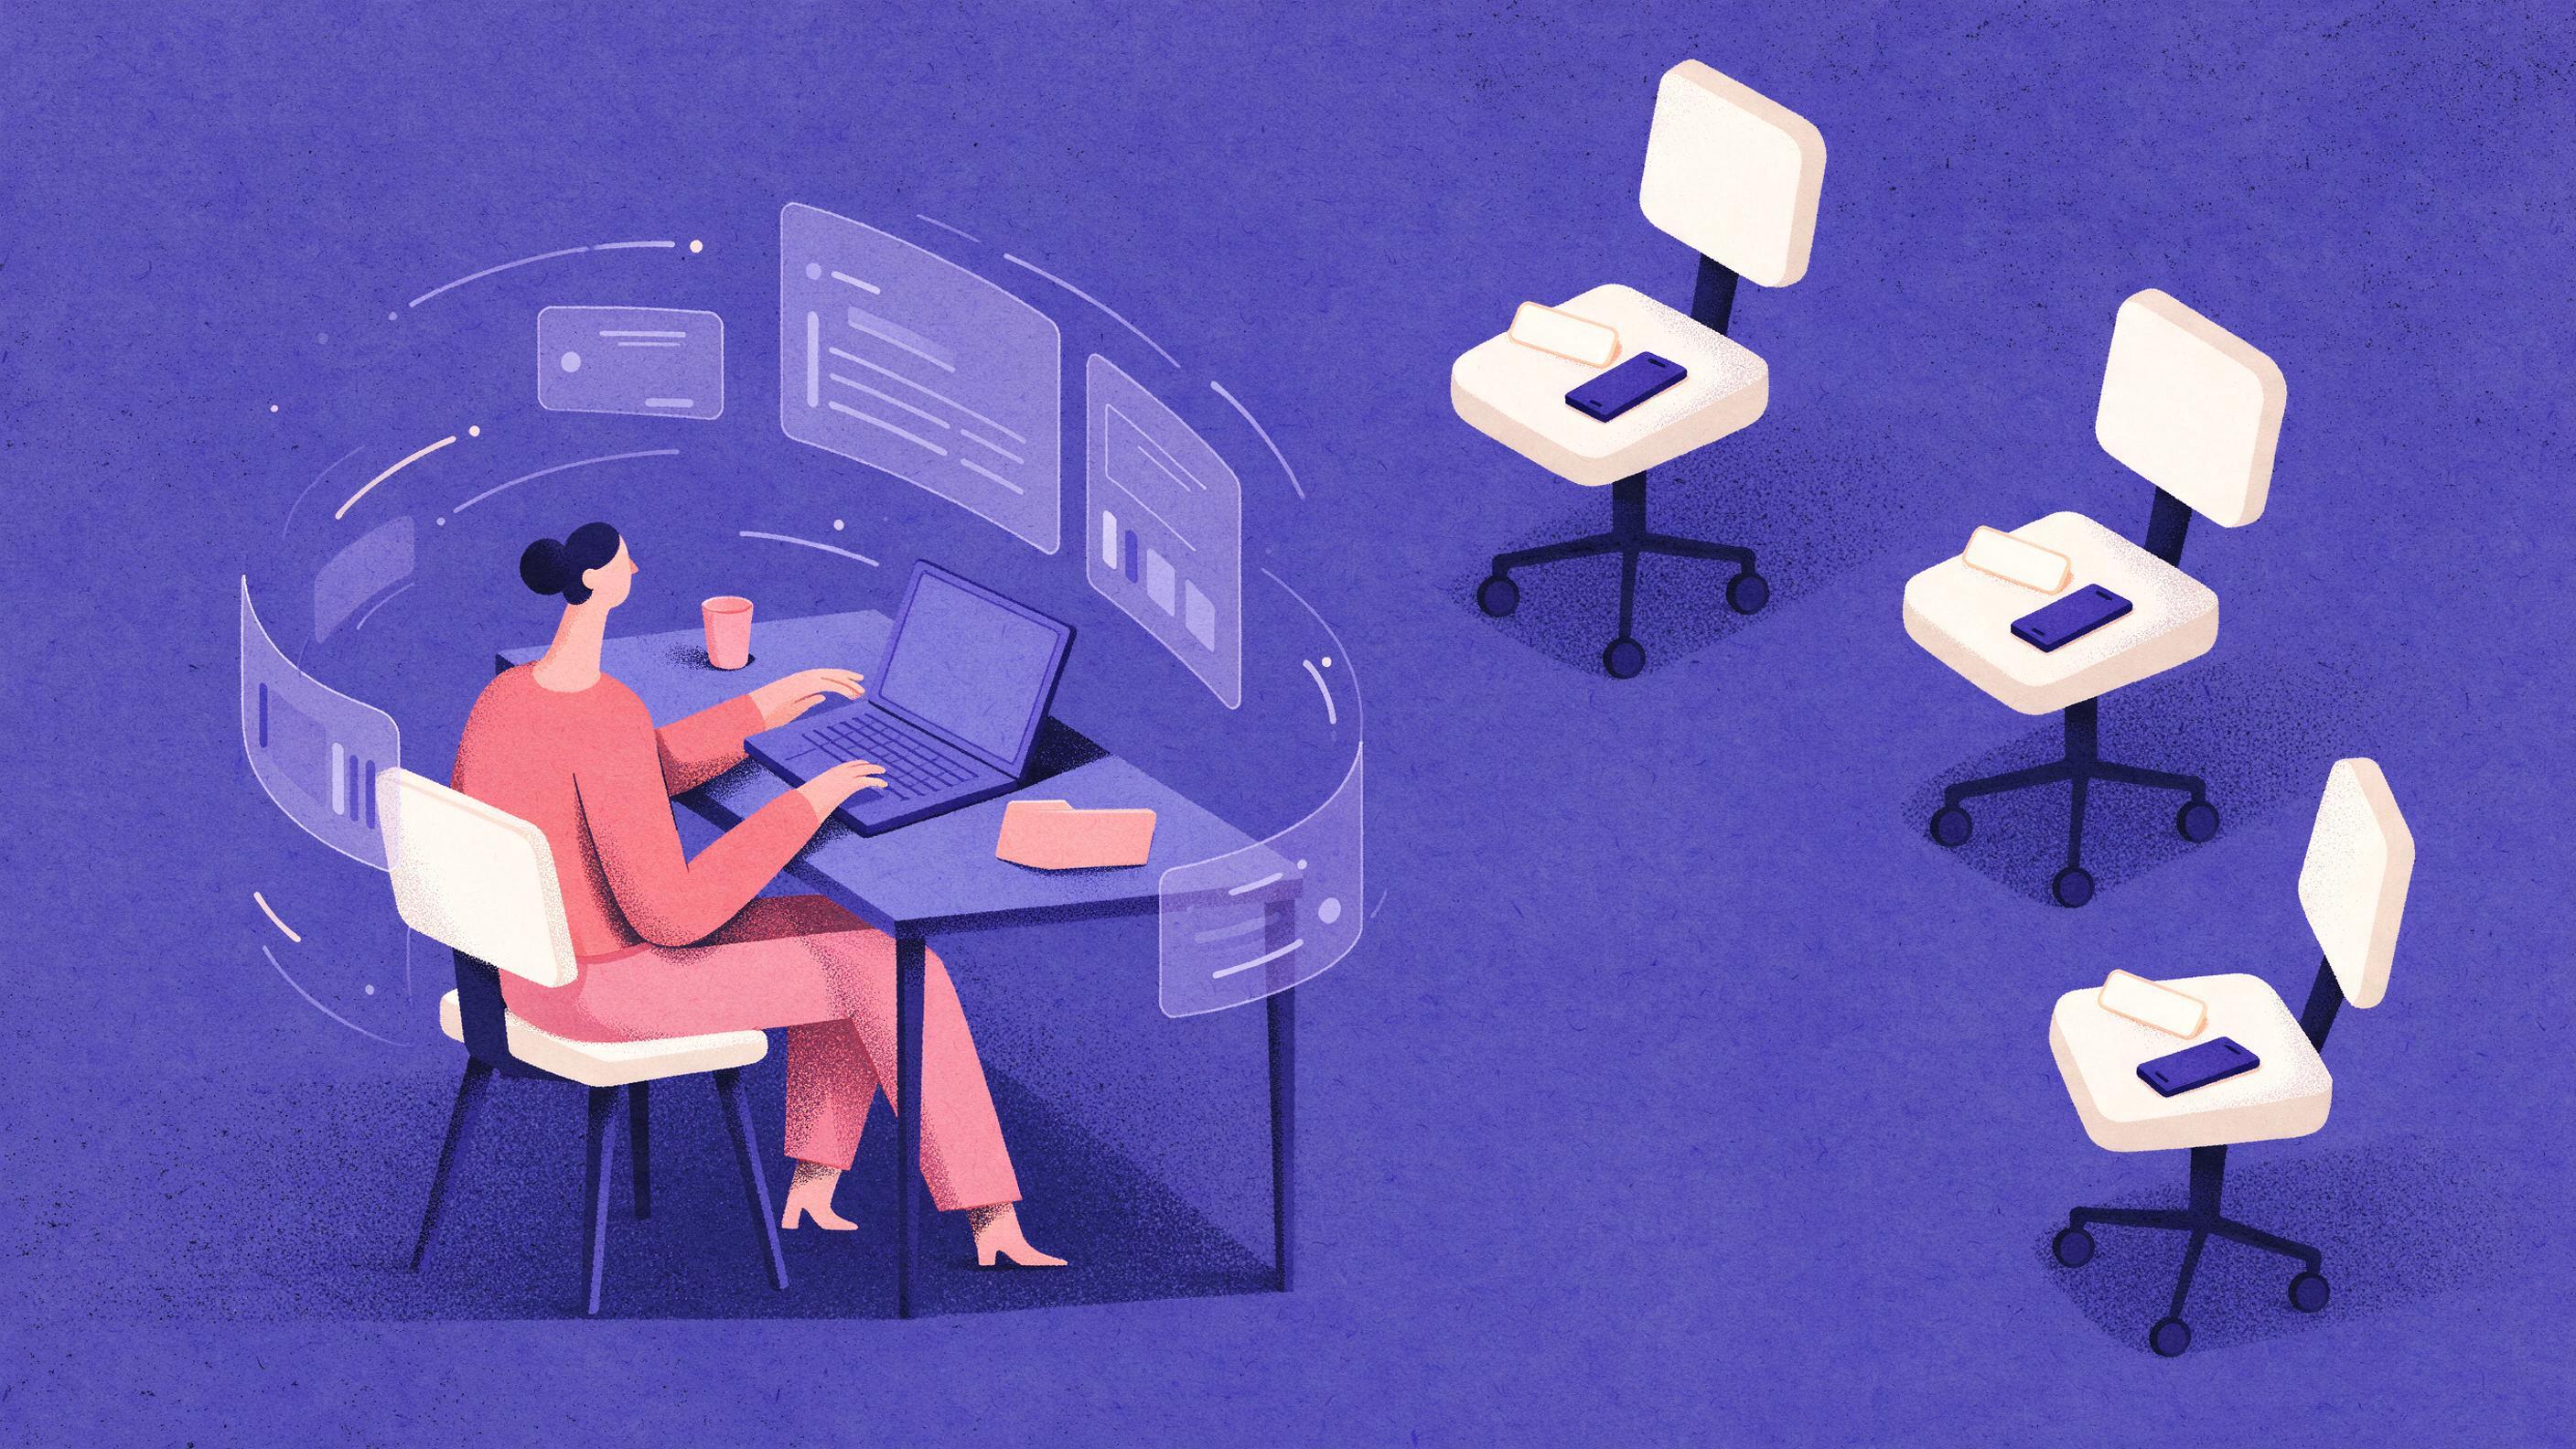
A single person at a desk with a laptop, three empty chairs arranged in a semicircle, each holding a name tag and a phone.
Key points

Key points

  1. 1A solo founder's real risk is dependency on one person, so the fix is structure: a small bench of advisors who each cover a gap you cannot hire for.
  2. 2Ask advisors for decisions, pattern recognition and introductions, not open-ended mentorship, and put a quarterly one-hour call on the calendar.
  3. 3Keep the bench alive with reciprocity and a written log of what you were told and what happened next.
  4. 4No cash or equity is required if the commitment is limited and you show their advice changed something.

Diagnose the gap before you recruit anyone

Most solo founders collect advisors the way they collect coffee meetings: anyone who will talk to them. That is the trap Matt Munson describes from his own first company, where he met "anyone who would meet me" and ended up with more charlatans than helpers, some of whom asked for steep equity in exchange for guidance that turned out to be thin Munson's account of finding advisors. The productive version starts one step earlier, with a diagnosis.

Techstars frames the diagnosis as a "who, not how" map: for every major bottleneck, ask who can help solve it, and classify whether the gap is an advisor issue, a contractor issue, a customer discovery issue, or something central enough that it needs a hire the Techstars advisor operating system. That distinction matters because a co-founder is not magic; it is a bundle of functions, and advisors can carry some of those functions without ownership or salary Techstars on the functions a co-founder provides.

The same piece is blunt about why this matters at all: the concern with solo founders is not loneliness but dependency, because one person holding the vision, customer relationships, product judgment and operating plan is a single point of failure Techstars on dependency risk. A bench does not remove that risk, but it distributes some of the judgment.

A workable diagnosis takes about an hour. Write down the three to five decisions that will most shape the next twelve months, things like pricing model, first hire, channel choice, or whether to raise. Next to each, write the name of the person you would call today. Blank rows are your gaps, and blank rows are what the bench is for.

One caution: an advisor is not a substitute for structure. A common answer to "do I need an advisor as a solo founder" is that most solo founders are not short on perspective, they are short on a business that does not depend entirely on one person practitioner discussion on solo founders and advisors. If a gap shows up in every row, the answer may be a fractional operator or a hire, not a quarterly call.
Where to find three to five advisors without paying a board

The people you want are usually not on advisor marketplaces. They are one or two hops from your existing network, and they are findable through channels that already filter for competence.

ChannelWhat it is good forWhat it filters outTypical first ask
Industry associations and trade groupsRegulatory, pricing and buyer-expectation pattern recognitionPeople with no operating history in your marketA 30-minute call about one specific decision
Alumni networks (school, former employer)Fast trust, shared context, willingness to take the first callStrangers who owe you nothingA short question by email, then a call if useful
Niche communities and founder roundtablesPeer-level challenge from people one stage aheadLurkers and pure networkersJoining a recurring session before asking for anything
Warm introductions from investors, customers or peersDomain experts for the next 12 to 18 monthsCold outreach that reads as a pitchAn introduction request with a one-line reason
Customer advisory input (a handful of buyers)Ground truth about the problemFounders' own assumptionsA structured feedback conversation every quarter

Two sourcing rules do most of the work. First, target a domain expert in an area that is critical to the company over the next 12 to 18 months, which is the criterion Munson puts first Munson on advisor selection. Second, prefer the person who will challenge you over the famous name. Techstars makes the point directly: many founders collect advisors, fewer build an advisor system, and the most useful advisors are not always the most famous, they are the ones who ask the hard question before the market does Techstars on advisor systems.

Communities work best when you show up before you ask. A free roundtable format where founders work through one specific business question at a time is a low-cost way to meet people who think in decisions rather than platitudes the 1Mby1M roundtable format. Treat the first two sessions as scouting: note who disagrees with you constructively, then ask that person for a single call.

Stage2 Capital's description of advisor structures is a useful sanity check on scope: a lightweight advisory relationship is often framed as roughly 1 to 3 hours per quarter over a 12 to 24 month term, with introductions, domain expertise and product feedback as the expected outputs Stage2 on advisor structures. That is the shape of commitment you are asking for. If someone wants a formal board seat, a vesting schedule and a monthly meeting, you are no longer building a bench.

What to ask for: decisions, pattern recognition, introductions

General mentorship is the least useful thing you can request, because it produces conversation rather than change. Replace "will you be my mentor" with three specific asks.

Decisions. Bring one to three named decisions to each call, each with the options you are weighing and the evidence you have. "Should we move from per-seat to usage pricing for teams above ten?" is answerable in ten minutes. "What do you think about our go-to-market?" is not.

Pattern recognition. You are buying the advisor's memory of similar situations. The question that unlocks it is comparative: "In the last five companies you saw make this move, what broke first?" That phrasing turns an opinion into a base rate.

Introductions. Ask for one warm introduction per quarter with a one-line reason and a forwardable paragraph you have already written. Introductions are the cheapest thing an advisor can give and often the most valuable thing you receive, which is why advisory relationships are commonly justified by access to prospects, candidates and investors HubSpot on advisory board benefits.

A short brief sent 48 hours before each call makes all three asks concrete. Something like this works:

ADVISOR BRIEF, Q3
Decisions I need help with (pick any):
1. Pricing: per-seat vs usage, evidence attached, deadline in 3 weeks
2. First hire: support vs sales, current load numbers attached
Pattern question: what broke first when you saw companies
make this pricing move?
Intro request: one person who has run usage pricing at
a 10-50 person B2B tool
What I did with your last advice: (2 lines)
What happened: (2 lines)

Keep the brief to one screen. Advisors on a manager's schedule can absorb a short document between meetings; they cannot absorb a business plan, and Paul Graham's distinction between maker and manager schedules explains why: a meeting is a unit of work for the manager and an interruption for the maker Graham on maker and manager schedules. Treat your advisor's calendar as the scarce resource and compress your request into something readable in five minutes Farnam Street's summary of the two schedules.

Set a cadence you can actually keep

The default that survives contact with real schedules is a quarterly one-hour call per advisor, plus short ad hoc requests by email or a shared document. Quarterly is enough to catch a decision before it hardens and infrequent enough that nobody feels managed.

Three design choices make the cadence stick. First, stagger the calls so you are not preparing four briefs in the same week; one advisor per month gives you a steady rhythm of outside input. Second, put each call at the end of your working day, the office-hours pattern Graham describes to keep advisory time from breaking up focus blocks Graham's office hours approach. Third, batch ad hoc questions: collect them in one document and send when you have three or when a deadline forces the issue, whichever comes first.

For the request itself, keep the commitment bounded and explicit. A short message beats a vague one:

Subject: Quarterly call, 1 hour, 4x per year

I'm building [one line]. I'd like to ask you four times a year
for one hour about specific decisions, plus the occasional
short email question. I'll send a one-page brief 48 hours
ahead and a two-line note afterward on what I did and what
happened. No equity, no formal board, and you can stop
after any call.

The cadence also sets your own review rhythm. A quarterly call is a natural forcing function for a written review of what you decided and what you learned, and David Allen's weekly review checklist is the canonical template for that habit at weekly scale: collect loose items, review projects and waiting-for items, and pick next actions Allen's weekly review checklist. A condensed version of the same six steps, adapted for a weekly personal review, is easy to reuse before each advisor call a practical GTD weekly review guide.

Keep the calls short for your own sake too. The mere-urgency effect is well documented: people gravitate to time-sensitive tasks over more rewarding ones, and self-described busy people are especially prone to it, which is why a scheduled call with a deadline is more likely to happen than a vague "let's catch up soon" Todoist on the mere-urgency effect. Put the date in the calendar and the brief in the invite.

One more scheduling note. If a call keeps slipping, the relationship is already over; cancel it explicitly rather than letting it rot on the calendar. A bench of three engaged advisors beats six names you never speak to.

Keep it useful: expectations, reciprocity, a written log

Advisory relationships decay for boring reasons: vague expectations, one-way value, and no memory. Each has a cheap fix.

Expectations. Say in writing what you want (a quarterly hour, short email questions, one introduction per quarter), what you will send (a brief before, a note after), and when you will check in about whether it is working. HubSpot's guide draws the mentor versus advisor line clearly: a mentor relationship is open-ended and unpaid, while an advisor relationship carries a stated time commitment and often a contract HubSpot on mentors versus advisors. You can stay in the mentor-like, unpaid zone as long as the commitment stays bounded.

Reciprocity. Give before you ask. Useful currencies for a solo founder include a customer introduction, a candidate referral, a short written summary of a market you researched anyway, or public credit when their advice shaped a launch. Reciprocity is not bribery; it is the reason a busy person keeps taking your call.

A written log. Keep one page per advisor with four columns: date, what you asked, what they said, what you did and what happened. This is the decision log idea in practice. Techstars recommends recording what you decided, why, what evidence you had, and what would cause you to revisit it, because it forces you to separate facts from assumptions and helps advisors and future team members understand how the company got where it is Techstars on the decision log.

Log columnWhat goes in itWhy it matters
Date and questionThe exact decision you broughtMakes the next call start where the last one ended
Advice receivedTheir recommendation in one sentenceSeparates their view from your interpretation
Action takenWhat you actually did, with datesReveals whether you are using the bench or collecting opinions
OutcomeThe result, in numbers where possibleThe feedback that keeps an unpaid advisor engaged

That last row is the whole game. Advisors who never learn whether they helped drift away, and founders who never record outcomes repeat the same conversations. A two-line "here is what I did, here is what happened" note after each call costs five minutes and is the single strongest retention tool you have.

When the bench is not enough

A bench handles judgment. It does not handle execution, and it does not scale past a certain volume of decisions. Watch for three signals that the gap has changed shape.

The first is repetition: if the same advisor gives you the same advice three quarters running and nothing changes, the constraint is capacity, not counsel. The second is centrality: if your progress depends on a capability you cannot credibly manage from the outside, Techstars calls that structural risk rather than a small gap Techstars on structural risk. The third is isolation: when founders are isolated their judgment can narrow and they can overvalue their own ideas, which is why the same piece treats anti-isolation habits as business infrastructure rather than a wellness concern Techstars on isolation as business risk.

When execution is the bottleneck, the answer is usually a contractor, a fractional operator, or a hire, and the cost of that is real. A free 30-minute consulting call is a reasonable way to pressure-test which of those you actually need before you commit budget Quanta Consulting. If what you need instead is to get the thing built, from a site to an internal tool, a specialist can pick it up with you Quanta.

The bench itself stays cheap. Keep it to three to five people, one decision per call, one introduction per quarter, and one log that proves the advice moved something. That is a board you can run alone.

FAQ

FAQ

How many advisors does a solo founder need?

Three to five is the working range: enough to cover distinct gaps, few enough that you can prepare a real brief for each one. Informal advisory groups of three to five people, each bringing expertise you are weaker in, are a common pattern among solo operators practitioner advice on informal advisory boards. Fewer than three and you get one worldview; more than five and the quarterly cadence collapses.

Do I have to give equity to advisors?

No, if the commitment is limited. Equity is the norm for formal advisory boards, where grants often run around 0.1% to 0.2% of outstanding equity per advisor, vesting over time, alongside a confidentiality agreement WilmerHale on advisory board compensation. A quarterly call plus short email questions sits below that bar, and reciprocity plus visible results is usually enough to keep people engaged.

What should a first advisor call cover?

One decision, brought with options and evidence, plus one pattern question about what broke in similar situations, plus at most one introduction request. Send a one-page brief 48 hours ahead so the advisor can think before the call. End by agreeing on the date of the next call and what you will report back.

How do I keep advisors engaged without paying them?

Send a two-line note after every call saying what you did with the advice and what happened. Give something back each quarter, such as an introduction, a referral or a short piece of research they can use. And be honest about fit: if a call keeps slipping or the advice is not landing, wind it down politely rather than letting it fade.

When should I replace an advisor or stop the relationship?

When the same advice recurs without progress, when their domain stops matching your next 12 months, or when they consistently miss the cadence. Replace them with someone who covers the new gap, and keep the log so the next advisor inherits the context instead of starting cold.

Sources

Sources

  1. How to find great advisors for your startup (and avoid the shit ...
  2. Solo Founders Are Riskier. The Best Ones Prove They're Worth the Bet.
  3. Techstars в X: „4. Use a “who, not how” map. Solo founders often ask ...
  4. I am the only founder of my company, do I need to find an ...
  5. Solo Founders Need an Operating System, Not Advice - YouTube
  6. Startup Founders: How to Find the Right Advisor for Your ...
  7. How To Structure an Effective Startup Advisory Board - HubSpot
  8. Maker's Schedule, Manager's Schedule - Paul Graham
  9. Maker vs. Manager: How Your Schedule Can Make or Break You
  10. PDF GTD Weekly Review® - David Allen
  11. GTD Weekly Review: 6-Step Checklist & Template - Super Productivity
  12. Avoid the "Urgency Trap" with the Eisenhower Matrix - Todoist
  13. Advisory board setup and compensation - WilmerHale Launch
About the author

About the author

Antonio Evans
Antonio Evans

Antonio Evans is the founder of Quanta Intelligence and a fractional CTO who builds HIPAA-ready AI systems for health and life-science companies. Before that he was technical co-founder of FriendsEAT for twenty years, CEO of Socialdraft, and a data engineer at IBM. Antonio lives with his dog Santino in Lisbon, Portugal.

All articles