Founders

How to Build an Investor Pipeline You Can Track

Antonio Evans11 min read

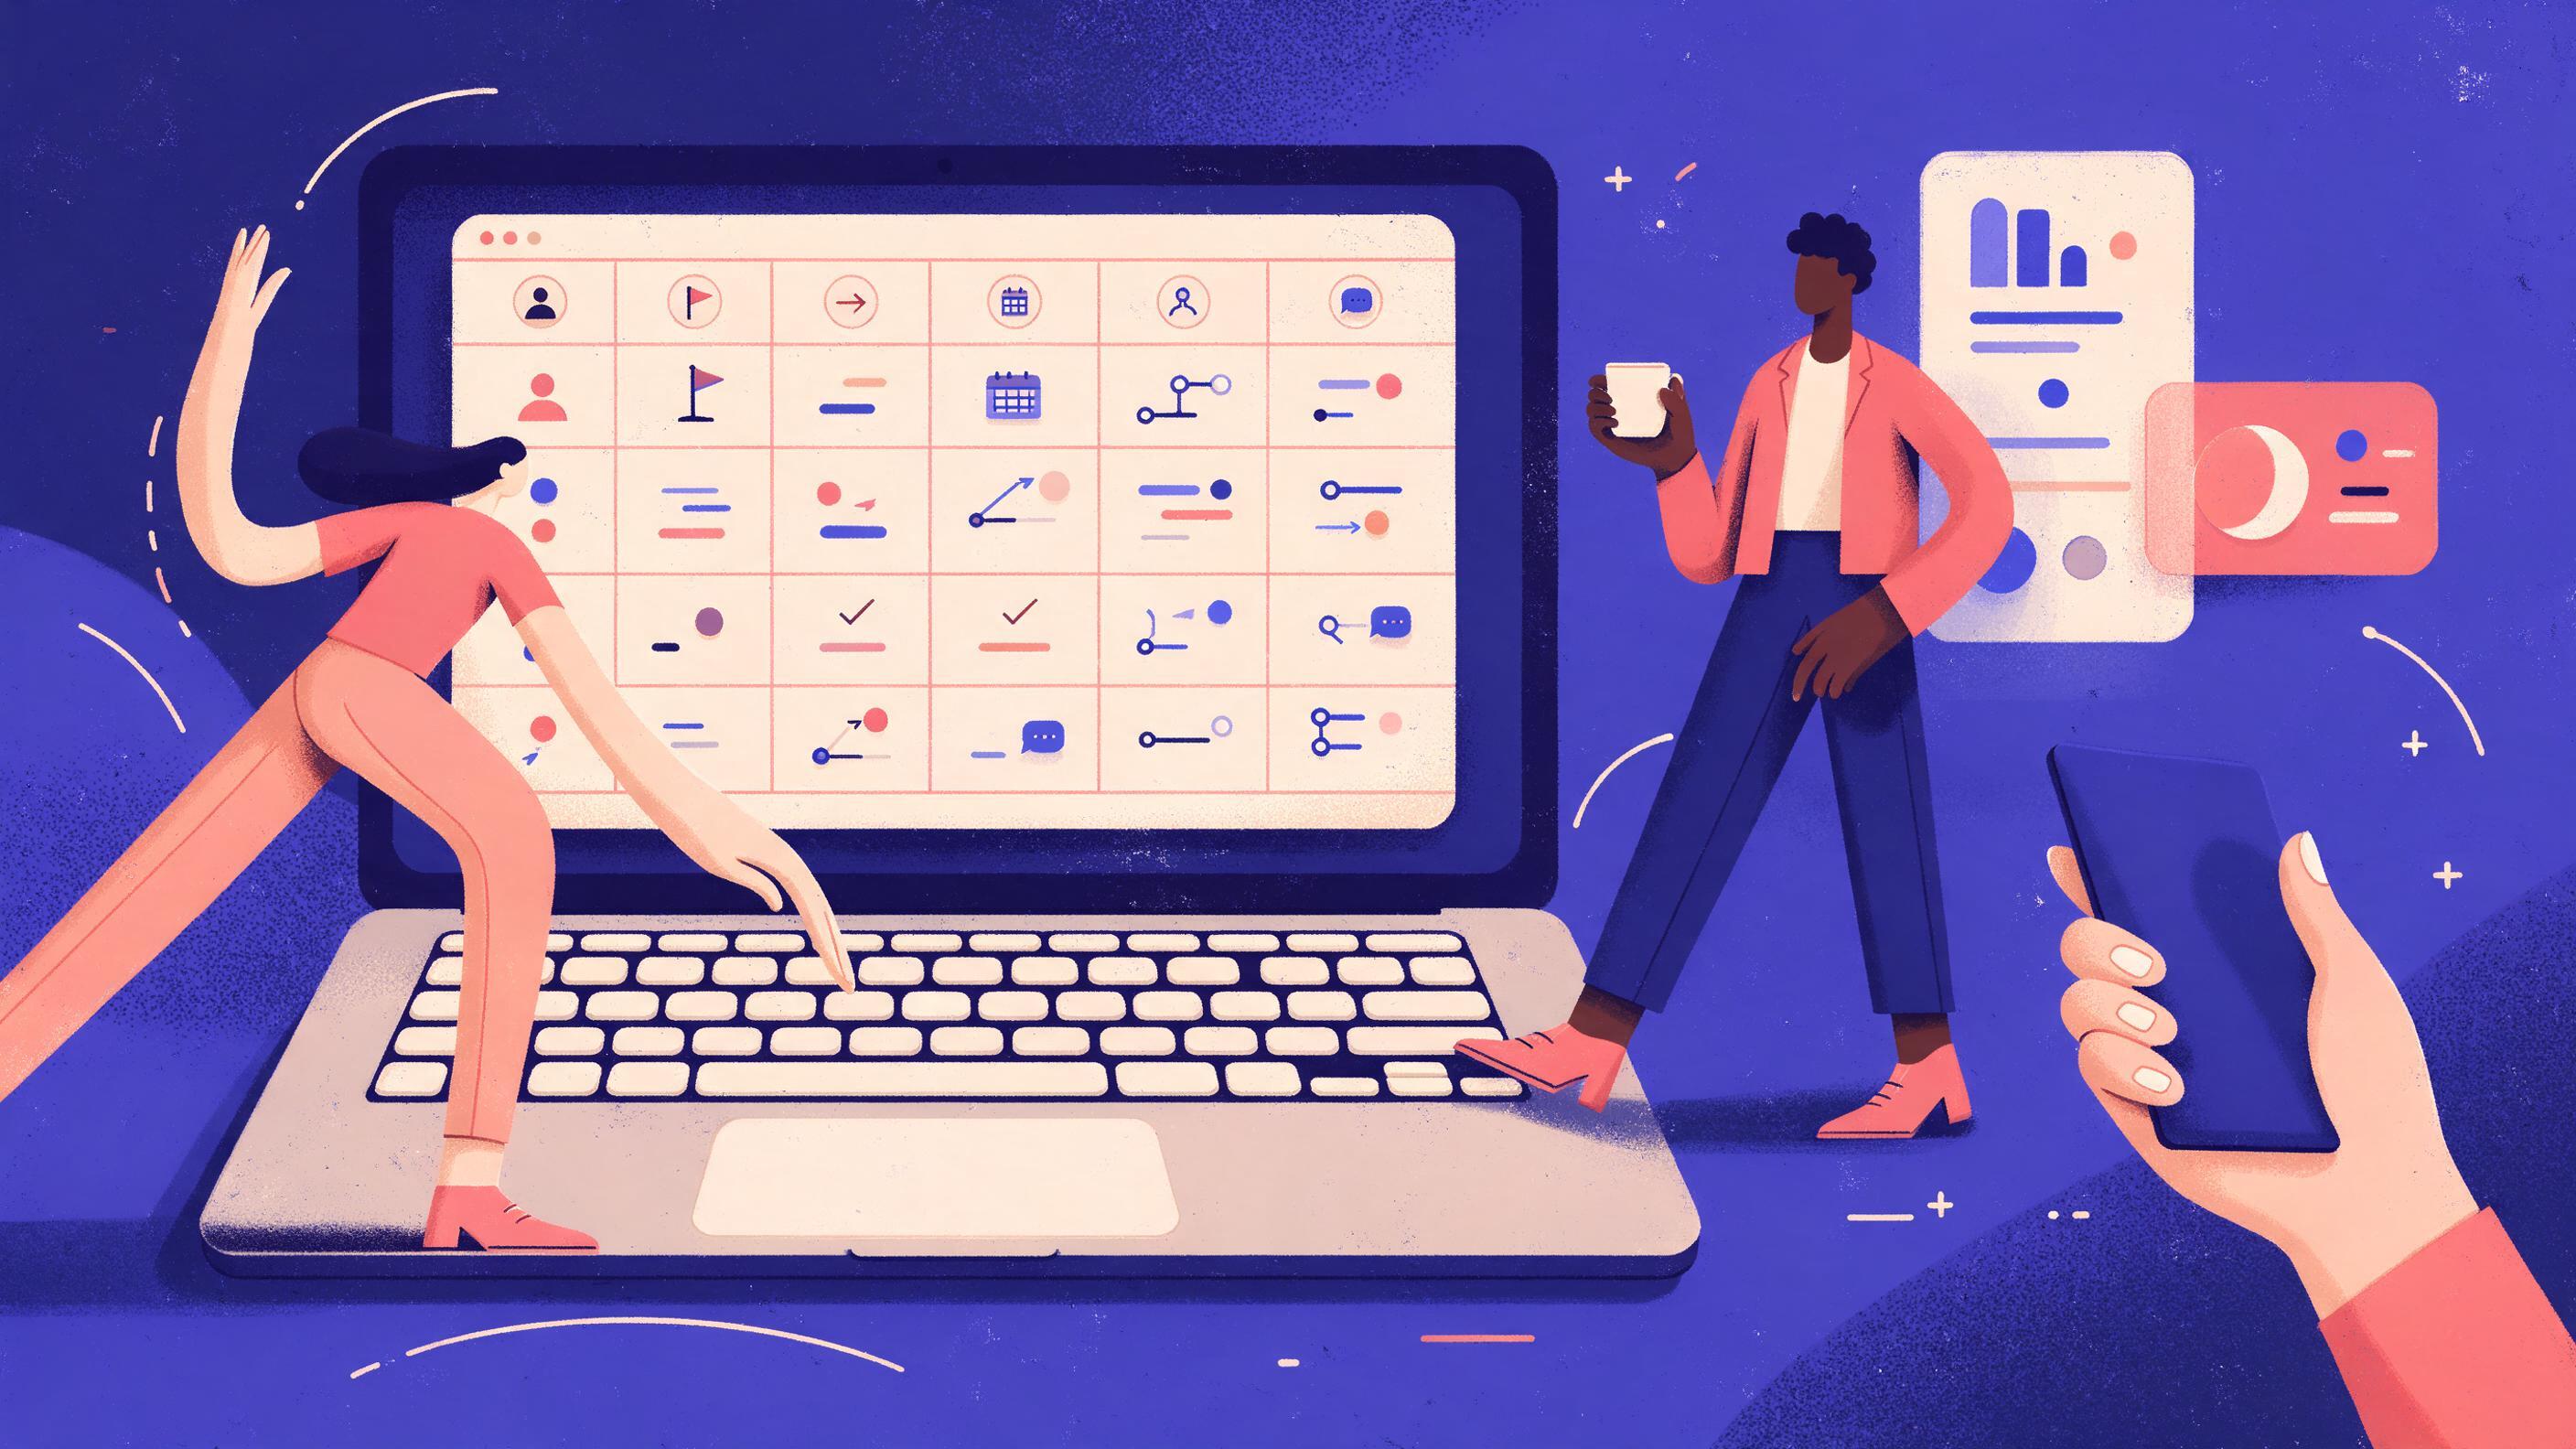
A top-down view of a laptop screen showing a simple spreadsheet with columns for investor name, stage, next action, next action date, warm intro path, and last contact.
Key points

Key points

  1. 1One spreadsheet with a fixed column set, a mandatory next action and a named owner per row is the whole system; anything looser drifts within two weeks.
  2. 2Stages should be defined by what the investor has actually done, not by how hopeful you feel about them.
  3. 3The warm-intro path is a specific person plus the exact ask, recorded on the row before outreach starts.
  4. 4Count rows per stage and the age of the oldest row in each to see whether the round is moving or stalling, then move or close every row with no next action.

Start with the columns, not the names

Most founders build an investor list first and figure out the tracking later. That order is backwards. The sheet's structure decides what you can see later, and columns you add in week six will be half-empty for every row you entered in week one.

Pick a fixed schema before you paste in a single name. There is no universal correct set, but the operating minimum is roughly fifteen columns, and every one of them should answer a question you will actually ask during the raise. If a column does not change a decision, delete it.

ColumnWhat it holdsWhy it earns its place
Investor / firmPerson and fund, one row per personTwo partners at one fund are two relationships
TierA, B or C by fitSets outreach order and how much time each row deserves
StageOne of six fixed values (below)The only thing you sort on during review
OwnerOne teammate's nameUnowned rows are the ones that rot
Next actionA verb and an object"Send deck" is not an action; "send deck to Priya by Friday" is
Next action dueA dateAnything undated never happens
Last touchDate of the last real contactFeeds the aging count
Warm intro pathPerson, relationship, exact askThe single highest-leverage field in the sheet
Check size expectedA range in dollarsKeeps the coverage math honest
SourceHow the name arrivedTells you which channels actually produce meetings
Objection / concernVerbatim, in their wordsThe input to your next update email
NotesFree text, datedCheap memory

Two rules make this schema work in practice. First, "next action" and "owner" are mandatory: a row cannot be saved without them, and if you cannot think of a next action, the honest entry is "close: no path forward." Second, dates are real dates in a date column, not text like "next week," so you can sort and filter on them.

OpenVC's guide to building an investor pipeline makes the same structural point: whatever tool you use, the pipeline should rely on clear stages with a clear gate at each one, and they warn against having more than about five because the middle of the funnel realistically holds only a dozen investors at a time the OpenVC pipeline guide.

You can set the mandatory fields up in a few minutes. In Google Sheets, put Owner and Next action on every row and use data validation plus conditional formatting to flag blanks in red. If you prefer a script, a short Apps Script trigger that emails you any row with an empty next action is enough.

function flagRowsWithoutNextAction() {
  const sheet = SpreadsheetApp.getActiveSheet();
  const values = sheet.getDataRange().getValues();
  const header = values[0];
  const nextActionCol = header.indexOf('Next action');
  const ownerCol = header.indexOf('Owner');
  const missing = [];
  for (let i = 1; i < values.length; i++) {
    const row = values[i];
    const stage = row[header.indexOf('Stage')];
    if (stage === 'Closed' || stage === 'Passed') continue;
    if (!row[nextActionCol] || !row[ownerCol]) missing.push(i + 1);
  }
  if (missing.length) {
    Logger.log('Rows missing owner or next action: ' + missing.join(', '));
  }
}
Define stages by investor behavior

The most common failure in an investor pipeline is a stage column that records the founder's optimism. "In discussion" can mean anything from a reply saying "not now" to a partner meeting booked for Thursday. When stages are fuzzy, the weekly review becomes an argument with yourself.

Tie each stage to an observable event that the investor caused. A workable six-stage set looks like this:

  • Sourced. You have a name, firm and a reason to believe they fit. No contact yet.
  • Contacted. An email or intro request has been sent. This is your action, not theirs.
  • Engaged. The investor has replied. A reply is the gate, and it is binary: no reply means still Contacted, no matter how promising the intro was.
  • Meeting held. At least one call or meeting has happened and notes are in the row.
  • Diligence. They have asked for specific materials, a data room, a customer call or a second meeting with a partner.
  • Committed / Closed. A signed SAFE, a wire, or a clear unconditional yes in writing.

A safe default instrument for pre-seed and seed commitments is the post-money SAFE, which Y Combinator ships in versions for valuation cap only, discount only, and MFN, with pro rata rights in an optional side letter rather than the main document Y Combinator's SAFE page. Having that document ready before you need it is part of the pipeline, because a committed investor who waits three days for paperwork is momentum you spent for nothing.

The behavioral rule applies to the downside too. "Passed" is a legitimate stage, and passes should be recorded rather than deleted. Techstars' tracking guidance recommends keeping passes visible precisely because an early no can flip into a yes once the round has momentum the Techstars pipeline worksheet.

A stage only counts if you can show the evidence in the same row. If the notes do not contain a date and a next step, the row is not in the stage you think it is.

Capture names in a way you can defend

The list itself is a research artifact. Quality of the initial source list determines your conversion rate more than any email template does.

Start with fit filters rather than a single alphabetical list. Stage fit (they write checks at your size), sector fit (they have invested in adjacent categories recently), and check-size fit are the three that do the work. startupfundraising.com suggests targeting 60 to 100 investors for a seed round and 40 to 60 for a Series A, and building the list from portfolio pages, investor databases and warm-intro requests to existing investors the startupfundraising.com pipeline overview.

Then tier the list so you approach it in waves. Fidelity's writeup of a seed raise, based on a Copybara case study, describes 100+ firms contacted, 80 meetings taken, 16 receiving documents, 7 offers and 3 investors signed, with the founder quoted on getting 90 to 95 percent no's the Fidelity Private Shares pipeline guide. Read that math before you decide your list of 20 is enough. Volume is not a vanity metric here; it is the denominator of every conversion rate you will compute later.

Record the source on every row. If a name came from a portfolio page, write "portfolio page, March." If it came from a founder who introduced you, write that person's name. Over a raise, the source column tells you which channels produced meetings and which produced noise, and it is the only way to improve the top of the funnel mid-raise.

One discipline: never add a name you cannot qualify in one sentence. "They invest in seed-stage B2B software and led a round in a company two steps ahead of us" is a qualification. "Looks relevant" is not, and rows like that consume review time every single week.

The warm-intro path field

If you take one thing from this article, take this field. Cold outreach has a low ceiling, and the numbers back it: cold email open rates have been reported around 27.7 percent with reply rates around 5.1 percent, while a large share of angel deal flow runs through trusted networks Metal's guide to warm-introduction tools. Whether or not those exact figures generalize to your market, the direction is consistent with every founder account: the intro beats the cold email.

The warm-intro path field has three parts, and all three are required for the field to be useful:

  1. The person. A named individual who knows both you and the investor. "Our network" is not a person.
  2. The relationship. How that person knows the investor, and how well. A former colleague of ten years is different from a conference acquaintance.
  3. The exact ask. The specific sentence you want the connector to send, and what you are asking them to do (forward a two-paragraph email, make an introduction, or simply mention you).

Example entry: "Path: Dana Ruiz (our angel, worked with Priya at Stripe 2019 to 2022). Ask: Dana forwards the two-paragraph note and says we are the strongest infrastructure team she has seen this cycle. Due: Thursday."

Techstars recommends preparing a forwardable email as part of the pre-raise materials, written so that the connector needs to do no work beyond hitting forward the Techstars pipeline toolkit. Keep that email in a doc, and paste its current version into the row notes so the connector and you are working from the same words.

The Free-form note is where you record the outcome. If Dana says no, the row is still alive: try the second-best path, and log it. Founders routinely find that the third path works after the first two decline, because the ask is small and people are more willing to forward than to vouch.

If a row has no warm path after honest effort, mark it as cold and move it to the back of the wave. Do not delete it. Cold rows are your fallback when the warm network is exhausted, and they are also evidence, at review time, of how much of the list is actually reachable.

The weekly review that keeps the sheet honest

A pipeline spreadsheet decays in a predictable way: rows accumulate, stages stop changing, and the sheet becomes a diary of hopes rather than a record of a process. The fix is a fixed weekly meeting with rules, not vibes.

Set a 45-minute slot, same day each week, with everyone who owns rows. The agenda is short and the order matters.

  1. Count the rows. Read out the count per stage. Write the numbers down, with the date, in a small history tab. Four or five weekly snapshots are enough to see a trend; without them you are guessing.
  2. Age every active row. Sort by last touch. Any row in Engaged, Meeting held or Diligence with no contact in 10 or more days gets discussed first. startupfundraising.com's cadence advice is blunt on this: never let anyone in the pipeline go 10 or more days without an update, because silence kills momentum the startupfundraising.com pipeline overview.
  3. Interrogate the next action. For each row, ask whether the next action is a real action with a date and an owner, and whether it is the highest-value action available. "Follow up" is not an action. "Send the customer case study and propose Thursday or Friday for a partner call" is.
  4. Apply the close rule. Any row with no next action, no reply after a defined number of touches, or a clear soft no gets moved to Passed with a one-line reason. This is the rule most teams skip, and skipping it is why sheets bloat.
  5. Update the coverage number. Sum expected check size across Committed and Diligence rows, and compare it to the round target. If coverage is below roughly 1.5x the target at the Diligence stage, this week's job is top-of-funnel, not follow-up.

That last check is the one founders underuse. A round stalls quietly: rows stay in Meeting held, nobody passes, nobody commits, and the founder reads the silence as progress. Counting rows in Diligence against the round target turns silence into a number, and a number is something you can act on.

Keep the review boring. No new columns, no restyling, no tool migration during the raise. Changes to the schema mid-raise cost you a full week of comparability every time.

Spotting a stalled round from the sheet

The counts and the ages are the diagnostic. You do not need a dashboard; you need three numbers read against last week's.

Symptom in the sheetLikely causeThe move
Many Contacted, few EngagedWeak intro paths or a first email that does not earn a replyRewrite the forwardable email; shift rows to warmer paths
Healthy Engaged, no Meeting heldScheduling friction or vague asksPropose two specific times in the first reply
Meetings held but no DiligencePitch is interesting but the ask is unclearEnd every meeting by naming the next step and the decision timeline
Diligence rows aging past two weeksMaterials are slow, or you are the bottleneckAssign an owner and a date to each diligence request
Total expected checks below target across Diligence and CommittedRound is not coveredPause follow-ups and run a top-of-funnel week
Every row's last touch is more than two weeks oldNo review happenedRun the review before any outreach

The math on coverage deserves its own line. Suppose you are raising $1.5M and your expected checks from Diligence and Committed rows total $900K. That is 0.6x coverage, and the round is not close; it is short by $600K of pipeline. A founder looking only at "six active conversations" would call that healthy. A founder reading the sum would spend the week sourcing, not polishing.

The same logic applies to aging. If the median age of rows in Meeting held is 21 days, the problem is not the investors; it is that no one is pushing the next step. Look at your own outbound: how many of those rows had a next action in the last week, and how many of those actions were yours. Usually the answer indicts the founder, not the market.

When the numbers say the round is stalled, the fix is rarely a better deck. It is usually warmer paths, more parallel conversations, and a shorter time between first contact and a specific ask. Treating the raise as a process with a denominator is the whole point of keeping the sheet.

Keeping the sheet honest under pressure

The pressure points are predictable, and each one has a rule that saves you.

The friendly maybe. An investor who says "keep me posted" is not a lead. Record the exact words in the objection field and set a next action with a date. If the date passes and nothing moves, close the row. Keeping friendly maybes in the active count inflates coverage and hides the gap.

The slow lead. When an investor is holding up momentum, give them one clear ask with a deadline, and if they miss it, move on the startupfundraising.com pipeline overview. Write the deadline in the next-action due column so the review enforces it.

The co-founder problem. If two founders both "own" the pipeline, nobody does. One owner per row, named. The other founder can be the second name in the notes.

The privacy problem. A shared sheet with investor names, check sizes and candid notes gets forwarded. Decide who has edit access and who has view access before you build, and keep the most sensitive commentary out of the sheet entirely. Techstars' process-starter email asks mentors to help with the pipeline and even offers to share it, which is a reasonable practice with a distilled version, not the full working file the Techstars pipeline worksheet.

The "we'll update it later" problem. The sheet is worth more up to date at 70 percent completeness than perfect and a week stale. Every meeting ends with the row updated before the next calendar block. That single habit, applied for the length of a raise, is most of the system.

If the round needs materials built around it, such as an investor-facing data room site, a one-pager or a simple tracker app your team can share, Quanta takes a description of what you need and a specialist builds it with you. That is the natural next step when the spreadsheet has outgrown its second tab.

FAQ

FAQ

How many rows should the pipeline have before I start outreach?

Enough to cover the round several times over. Published guidance suggests 60 to 100 investors for a seed round and 40 to 60 for a Series A, and a documented seed case study shows 100+ firms contacted to reach 3 signed investors the startupfundraising.com pipeline overview the Fidelity Private Shares pipeline guide. If your list has 20 rows, you are under-sourced before you send a single email.

What is the right number of stages?

Six or fewer, each with a gate defined by investor behavior. OpenVC's guide warns against more than about five stages because the funnel realistically holds only a few investors in the middle at once the OpenVC pipeline guide. More stages create more places for a row to sit without anyone noticing.

How often should I update the sheet?

Update the row during or immediately after every call, and run the full review weekly. Any row without contact for 10 or more days should be treated as an emergency, since silence is what kills momentum the startupfundraising.com pipeline overview. Daily updates sound disciplined but usually mean the review never happens.

When should I move an investor to Passed?

When the next action has no answer after a stated deadline, when they say no or "not now" in any form, or when the row has no reachable warm path and cold outreach has failed twice. Record the reason in one line. Passes stay visible so you can revisit them if the round gains momentum, a practice Techstars recommends the Techstars pipeline worksheet.

Do I need a CRM instead of a spreadsheet?

Not necessarily. A spreadsheet with fixed columns, mandatory next actions and a weekly review covers most raises, and purpose-built CRMs mainly save typing and add reminders. What matters more than the tool is consistent stage updates, notes after every meeting, and the weekly review the startupfundraising.com pipeline overview. Move to a CRM when two or more people are updating rows daily.

Sources

Sources

  1. How to Build an Investor Pipeline for Startup Fundraising - OpenVC
  2. The SAFE
  3. Build Your Investor Pipeline Worksheet
  4. Investor Pipeline: Build, Prioritize, Run Your Fundraise
  5. Startup Fundraising: How to Manage Your Investor Pipeline
  6. The Best Tools to Find Warm Introductions to Investors in 2026
  7. Building Your Investor Pipeline - Techstars Entrepreneur's Toolkit
About the author

About the author

Antonio Evans
Antonio Evans

Antonio Evans is the founder of Quanta Intelligence and a fractional CTO who builds HIPAA-ready AI systems for health and life-science companies. Before that he was technical co-founder of FriendsEAT for twenty years, CEO of Socialdraft, and a data engineer at IBM. Antonio lives with his dog Santino in Lisbon, Portugal.

All articles