Founders

How to Write a Business Plan for an Investor Meeting

Antonio Evans10 min read

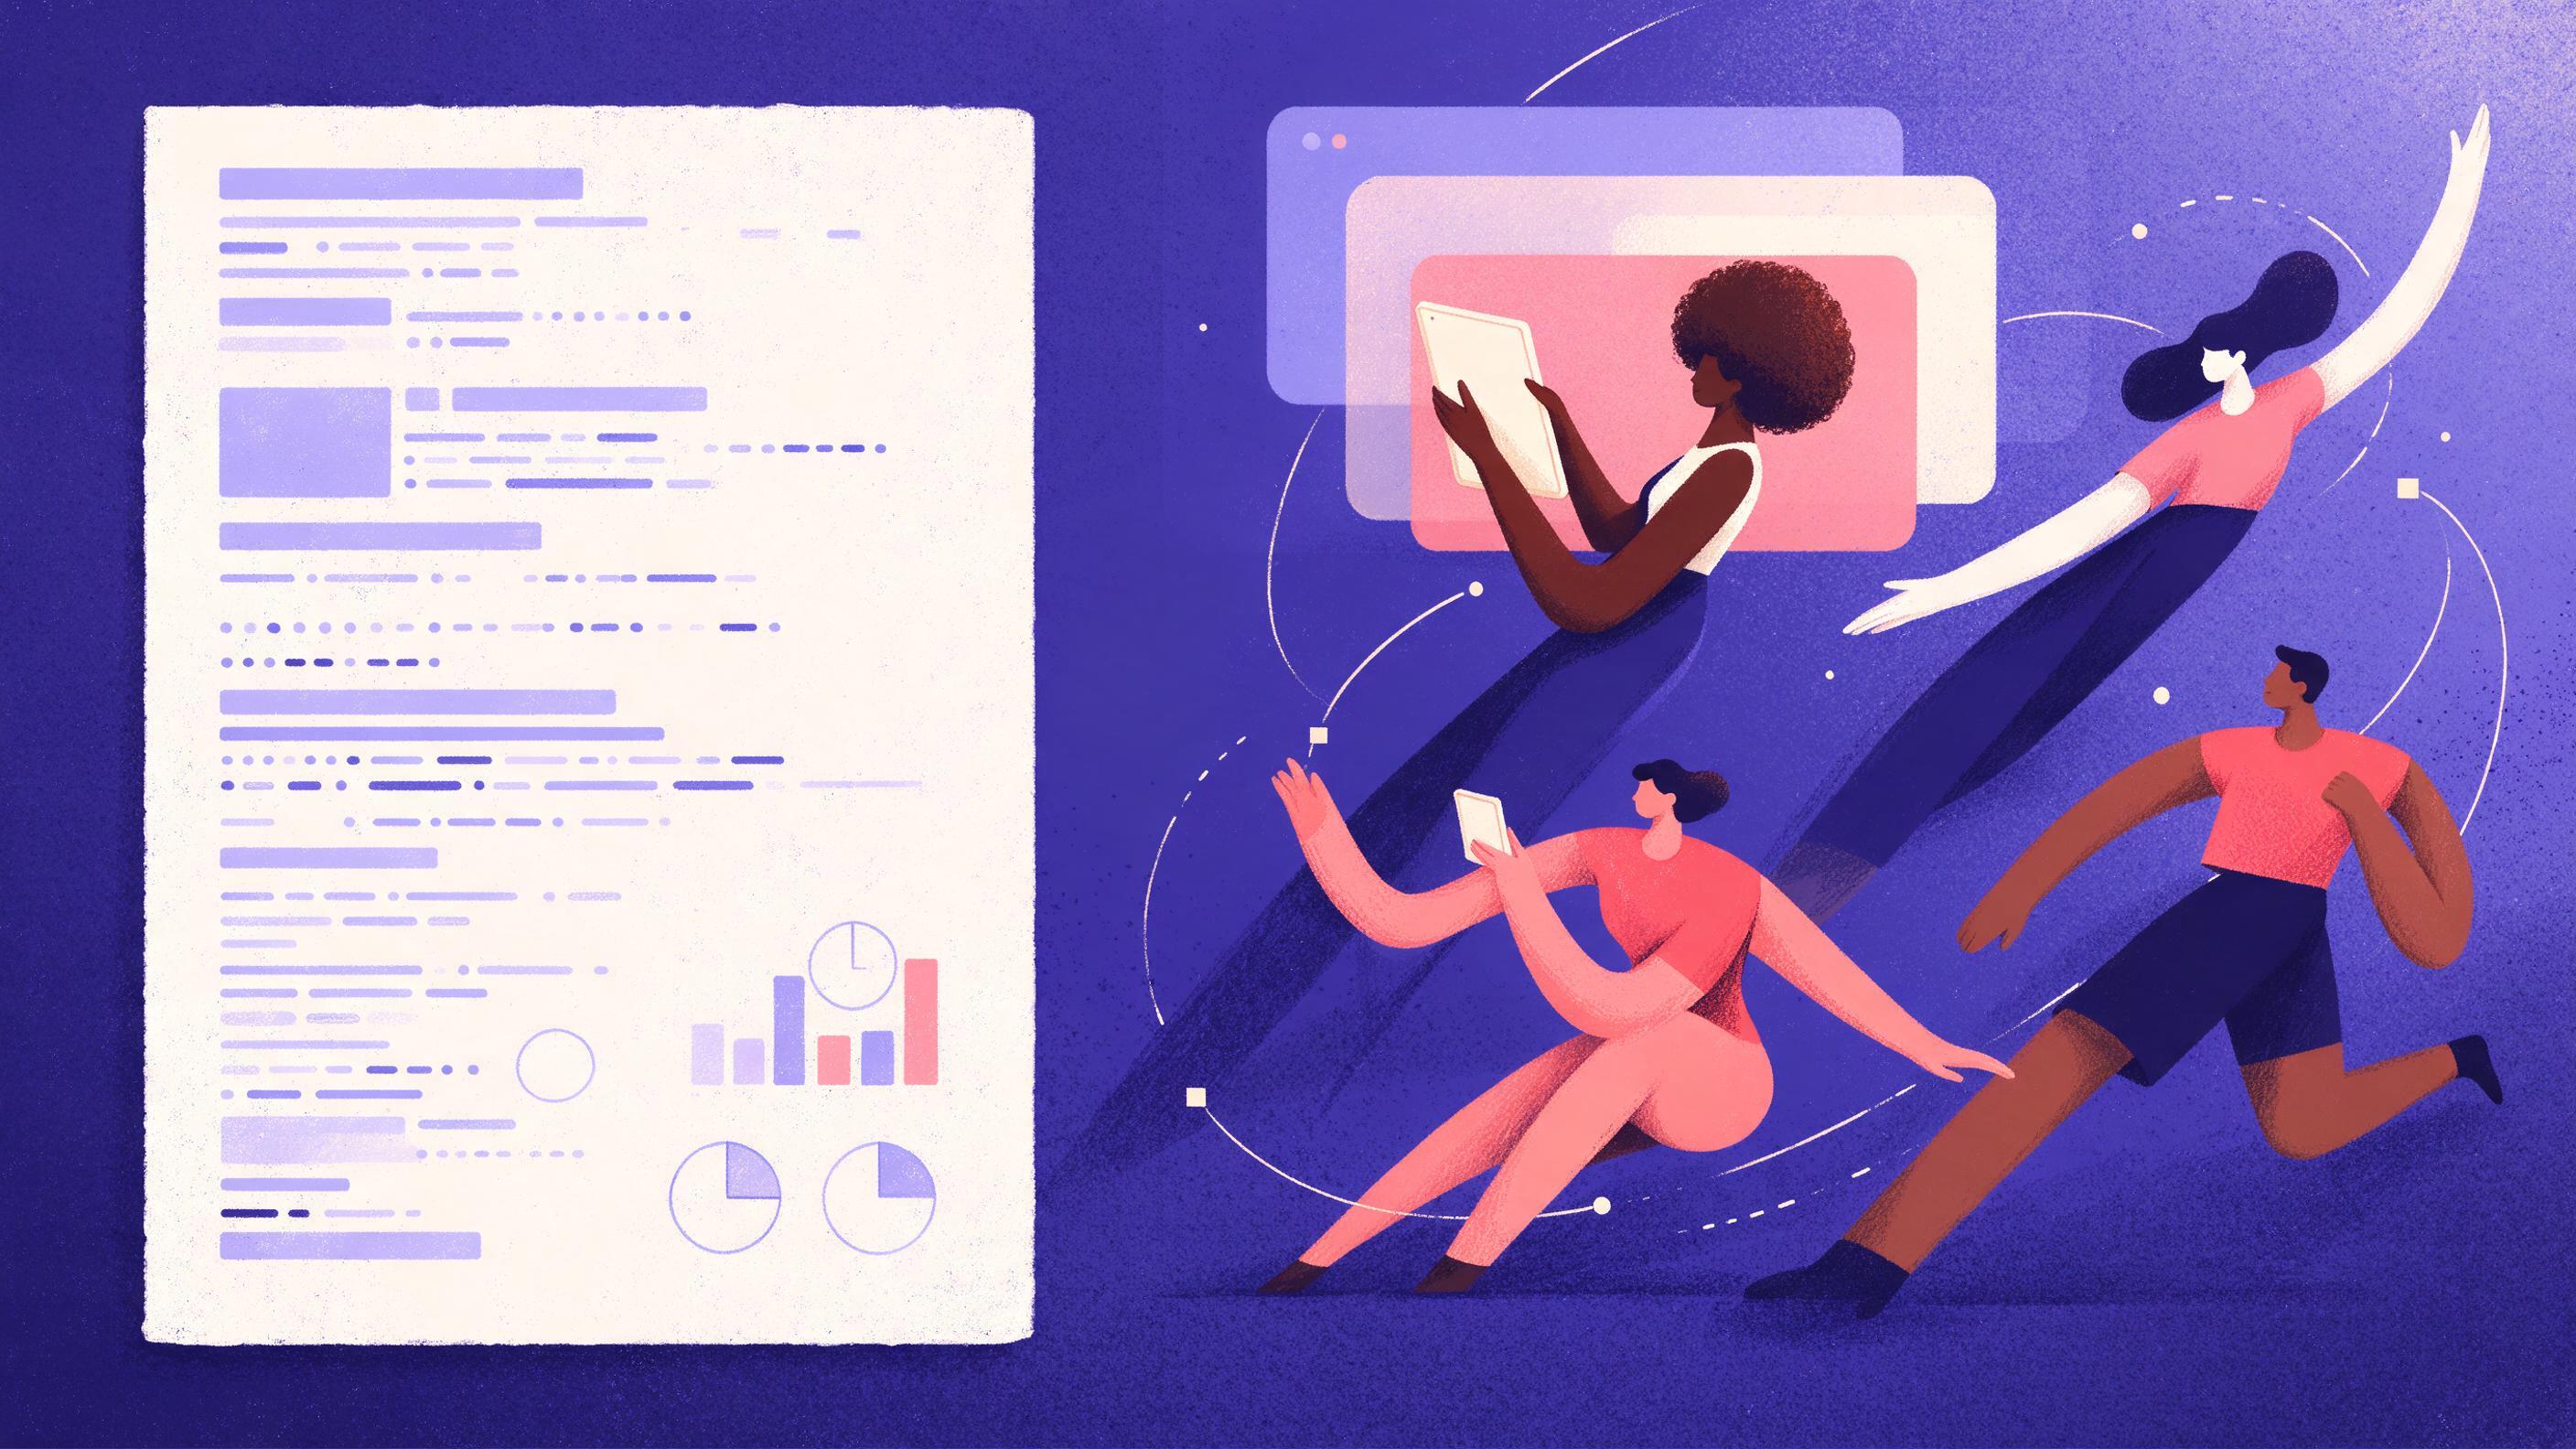
A split-screen illustration: on the left, a dense one-page business plan with numbered sections and small text; on the right.
Key points

Key points

  1. 1An investor meeting needs two artifacts, a spoken narrative under ten minutes and a deck of eight to twelve slides, not a reformatted one page plan.
  2. 2The one-page plan is your internal map; the meeting version reorders the same facts so the problem and the customer come first.
  3. 3Traction goes on a slide with a number and its source, and the ask and use of funds go on the last slide, stated plainly.
  4. 4Everything else (full market model, org chart, detailed financials) moves to an appendix you open only when asked.

Why the meeting document is not the plan

A one-page business plan exists to force you to decide what the business is. Templates for it ask you to fill in a business opportunity, target market, industry analysis, company description, timeline, marketing plan, financial plan and funding requirements, then compress all of that onto a single page the HubSpot template. That is a thinking tool. It is dense on purpose, because density is what makes you confront gaps in your own logic. A live audience cannot absorb that density, and reading it aloud is not a pitch.

The lean tradition makes the same point from a different direction. Ash Maurya, who created the Lean Canvas as an adaptation of the Business Model Canvas, argues that the goal of a one-page canvas is not perfection but a snapshot, and that if you cannot describe an idea on a single page it is probably too complex to explain Maurya's guide. Note the direction of travel: from many pages to one. An investor meeting moves the other way along a different axis. You take the one page, keep its factual spine, and rebuild it for a live listener: fewer slides than sections, a narrative you can actually say, and a supporting appendix.

The two documents also answer different questions. The plan answers "what is true about this business?" The meeting answers "should I keep listening?" Those are not the same question, and the order in which a reader or listener needs the answers differs. A plan can open with a company summary; a meeting cannot, because nobody yet cares who you are.

ElementOne-page planInvestor deckSpoken narrativeAppendix
Problem and customerOne line eachOne slide, two at mostFirst 60 to 90 secondsCustomer interview quotes
Market sizeA number with a methodOne number with its sourceOne sentenceFull model, bottom-up build
SolutionShort descriptionOne slide, product in use60 secondsScreenshots, architecture
TractionFinancial summaryOne slide, metrics and source90 seconds, the proofCohort tables, contracts
CompetitionCompetitor list2x2 or feature matrix30 secondsFull feature grid
TeamManagement and organizationOne slide, three faces30 secondsFull resumes, org chart
Ask and use of fundsFunding requirementsFinal slide30 seconds, exactDetailed budget
Financial projectionsFinancial planUsually absent or one lineReferenced, not recitedMonthly model

The column that surprises founders is the fourth. Everything that gets cut from the deck does not disappear; it goes into a section you keep closed, which is exactly why you can afford to cut it.
Layout the deck before you write a word

Commit to a slide count and a purpose for every slide before you touch design. A working structure that eight to twelve slides can carry:

  1. Title: company name and the one sentence that says what you do.
  2. Problem: who has it and what it costs them.
  3. Solution: what the product actually does, shown, not described.
  4. Why now: the change that makes this buildable or sellable today.
  5. Market: one number and how you derived it.
  6. Traction: the proof slide.
  7. Business model: how money arrives.
  8. Competition: where you sit and why that position holds.
  9. Team: three people and the specific reason each matters.
  10. Ask: amount, use of funds, milestones it buys.

Guidance from J.P. Morgan's startup banking team lists the same core components and emphasizes that a shorter deck requires just as much research and analysis as an old-style lengthy business plan the J.P. Morgan pitch deck guide. The compression is work, not laziness.

A useful test before you build slides: write the entire spoken narrative first, in plain paragraphs, on one page of your own. If a slide does not support a sentence in that narrative, it is not a slide, it is an appendix item. This keeps the deck from becoming a document with page numbers.

The opening two minutes decide the rest

Investors are pattern matchers under time pressure. One investor who has reviewed more than 14,000 decks describes silently checking a mental box against each expected section and asking questions only about the missing ones the VC's deck framework. Your opening should fill the most important boxes in the order a listener needs them.

The first two minutes should do exactly four things:

  • Name the customer and the pain. Not the industry, the person. "Finance teams at mid-size logistics companies close the month in eleven days because reconciliation is manual" beats "the reconciliation market is large."
  • Show the cost of the pain. A number, ideally from your own interviews. J.P. Morgan's guidance is explicit: incorporate data, such as statistics or market research, and explain why the problem needs solving now the J.P. Morgan guide.
  • Say what you built, in one sentence, in plain words. No category jargon invented that morning.
  • Give one piece of proof. One customer, one number, one signed contract. It signals that the next eight minutes are worth hearing.

What to leave out of the opening: your personal biography, the history of the idea, the size of the market, and any slide you would need to read aloud. Save the team for slide nine, where it answers a question the listener is already asking ("can these people do it?").

A worked example of timing for a ten-minute narrative:

WindowContentSlides on screen
0:00 to 1:30Customer, pain, cost of the painProblem
1:30 to 2:30What you built, in useSolution
2:30 to 3:30Why the timing is rightWhy now
3:30 to 5:00Traction, with sourcesTraction
5:00 to 6:00Market size and how you derived itMarket
6:00 to 7:00Business modelModel
7:00 to 8:00Competition and your positionCompetition
8:00 to 8:45TeamTeam
8:45 to 10:00Ask and use of fundsAsk

That is ten minutes with room to breathe. Most meetings allot far more time to questions than to the pitch, so the narrative is a setup, not the event.

Traction is the slide investors actually study

If there is one slide to over-invest in, it is traction. For early-stage companies, data on product demand carries weight, and the right metric depends on the model: customer lifetime value against acquisition cost for direct-to-consumer, monthly or annual recurring revenue for B2B software the J.P. Morgan guide. Choose the metric a knowledgeable investor in your category would ask for, and put that one on the slide.

Three rules for the traction slide:

  • Every number carries its source and its date. "MRR $48,000, from the billing system, as of the last month close" is a fact. A big number with no provenance invites suspicion.
  • Show the trend, not just the level. A chart with three to six data points beats a single figure, because it lets the listener see direction.
  • Name the denominator. "40 customers" means little. "40 customers out of 61 pilots started" tells the listener your close rate, which is a stronger signal than the total.

There is a real disagreement about whether to show forward financial projections at all. One pitch deck firm argues that in most pre-seed and seed pitches a financial projections slide hurts, and that it should appear only at Series A or later, when the investor asks, or when existing traction makes the next period close to deterministic; when included, they recommend five numbers at most, revenue, growth, gross margin, burn and runway, with every assumption defensible in 30 seconds the projections slide analysis. That is a defensible default. The full model belongs in the appendix either way, and the decision rule is simple: if the projection is not anchored to current pipeline, it does not go in the main deck.

For a session where you are building a new product or model and want the numbers checked before they reach an investor, a working session with a specialist can save a round of rebuilds: Quanta takes a description of what you need built and pairs you with someone who builds it with you.

The ask, and the four minutes after it

The ask is where many decks quietly fail. J.P. Morgan lists making the ask among the components founders most often forget, and it should show the investor both the size of the round and the relevant terms the J.P. Morgan guide. An ask slide needs four things and nothing else:

  1. The amount, stated as a single figure.
  2. The instrument and stage, for example a priced seed round or a convertible note.
  3. Use of funds, broken into three or four named buckets with percentages.
  4. The milestones the money buys, with dates, so the listener can see what the next round looks like.

A use-of-funds breakdown that reads "engineering 50 percent, go-to-market 30 percent, operations 20 percent" is fine only if the milestone sentence explains what each buys. Better: "50 percent engineering funds the integrations that unblock the three enterprise pilots; 30 percent go-to-market hires two account executives for the segment already buying; 20 percent operations covers twelve months of runway." Now each percentage is a decision, not a habit.

The appendix is what makes a short deck safe. Load it with the full financial model, the bottom-up market build, cohort retention tables, the complete competitor feature grid, customer contracts with names redacted, and the org chart. Say once, early, that it exists and that you will leave it behind. Do not present it. An investor who wants a specific number will ask, and handing over the exact slide in ten seconds is a stronger signal than a slide you read aloud.

Appendix checklist (build every item, present none):
[ ] Monthly financial model, 24 months forward
[ ] Bottom-up market sizing with each assumption listed
[ ] Cohort retention table by signup month
[ ] Full competitor feature grid
[ ] Two or three customer references with contact details
[ ] Technical architecture one-pager
[ ] Team resumes and full org chart
[ ] Cap table summary
[ ] Data room index

The cap table is worth a note. It is rarely a main-deck slide and almost always an appendix item, because a listener who asks about ownership is already engaged. Keeping it out of the main flow avoids raising a question the room was not yet ready to ask.

What to leave out, and why each cut helps

Cuts feel like losses. Reframe them: every item you remove from the main deck lowers the cognitive load on the listener and raises the odds they remember the thing that matters. The standard argument for the one-page format applies with more force to a live meeting: a shorter document is easier to read to completion, condenses your thinking, and removes unnecessary elements Indeed's one-page plan guide. In a meeting, the "reader" is also deciding whether to keep listening, which makes the tolerance for fluff lower still.

Leave these out of the main deck:

  • The full market model. One number and its derivation method go on the slide; the build goes to the appendix. A model with forty rows of assumptions reads as anxiety, not confidence.
  • The org chart. An investor wants to know whether the three people most responsible for the outcome can do the job. Names, roles, one line of relevant evidence each. The rest is appendix.
  • Long financial tables. Unless the traction story requires a forward view, keep projections out of the main flow and let the appendix carry the model, in line with the five-number rule described above the projections slide analysis.
  • Any slide you would have to read aloud. If a slide exists to be narrated word for word, it is a document. Delete it or turn it into a chart with one label.
  • Mission and values slides. They belong in a hiring deck. In a funding meeting they displace a slide that could carry proof.

Leaving things out works because the appendix is a promise you can keep. Present the shape of the business, then show that you have the detail ready. That combination, a short confident main body and a deep appendix, is what a prepared founder looks like.

If the meeting is a pre-read and you need the deck and the appendix built as a clean, shareable package rather than a folder of drafts, that is the kind of build Quanta specializes in. It is also the point at which a free 30-minute discovery call is worth taking: bring the one-page plan and the narrative draft, leave with a recommendation on structure.

Rehearse the transitions, not the words

The last thing to build is the glue. Founders rehearse individual slides and then stumble between them, which reads as uncertainty exactly when the listener is forming a view. Rehearse the sentences that connect slides, because those sentences carry the logic of the argument.

Three transitions do most of the work:

  • From problem to solution: "So the question is whether this can be automated, and that is what we built."
  • From solution to traction: "It works; here is what happened when we put it in front of customers."
  • From traction to ask: "Which is why this is the moment, and here is what the money does."

A practical rehearsal method: time the narrative with a stopwatch and stop talking at ten minutes, every time, even if you have not reached the ask. Run it three times with someone who has not seen the deck and ask them afterward to name the customer, the proof number and the ask. If they cannot, the narrative is not the problem; a slide is.

For teams building a live demo or a data dashboard into the meeting itself, an inference layer behind it keeps the demo from becoming the risk: Quanta Inference serves text, image, video, audio and embedding models through one OpenAI-compatible API key with prepaid pricing in US dollars, which means the demo does not depend on a single vendor's outage.

The one-page plan did its job when it forced you to decide what the business is. The meeting does a different job: it asks you to prove, out loud, in a order a stranger can follow, that the decision was right. Strip the plan down to problem, customer, proof, ask, and rehearse the walk between them. The appendix carries the rest.

FAQ

FAQ

How long should the spoken narrative be if the meeting is scheduled for an hour?

Assume ten minutes or less for the prepared narrative and treat the rest as questions. The narrative exists to create good questions, not to fill the calendar. If you run long, the room runs out of time to ask the questions that actually decide the outcome.

Where do detailed financial projections belong?

In the appendix by default. One analysis of hundreds of pitch decks argues a projections slide hurts more than helps at pre-seed and seed and should appear only with real traction behind it, or when the investor asks the projections slide analysis. When included, keep it to about five numbers with every assumption defensible in half a minute.

Can I just reformat my one-page plan into slides?

You can reuse the facts, but not the order. A plan can open with a company summary because the reader already chose to read it. A meeting has to earn attention, so the customer's problem comes first, the proof second, and the company description barely appears at all the J.P. Morgan guide.

What should the traction slide show if I have almost no revenue?

Show the strongest demand signal you have and name its denominator: pilots started, signed letters of intent, waitlist conversion, interviews where the customer named a price they would pay. J.P. Morgan's guidance is that early demand data goes a long way, and that the relevant metric depends on the industry the J.P. Morgan guide.

How do I decide what goes in the appendix versus the main deck?

Use one rule: if a slide supports a sentence in your ten-minute narrative, it belongs in the deck; if it answers a question you expect but do not need to raise, it belongs in the appendix. Then build every appendix item anyway, because the value of the appendix is that it is ready when asked.

Sources

Sources

  1. One Page Business Plan Template - Word, PDF - HubSpot
  2. What is a Lean Canvas? - Ash Maurya
  3. Creating an Investor Pitch Deck for Your Startup
  4. Ask a VC: what is a good pitch deck? - Medium
  5. Financial Projections Slide: Skip It or Nail It (2026 Guide)
  6. How To Write a One-Page Business Plan in 5 Steps (Plus Tips) - Indeed
About the author

About the author

Antonio Evans
Antonio Evans

Antonio Evans is the founder of Quanta Intelligence and a fractional CTO who builds HIPAA-ready AI systems for health and life-science companies. Before that he was technical co-founder of FriendsEAT for twenty years, CEO of Socialdraft, and a data engineer at IBM. Antonio lives with his dog Santino in Lisbon, Portugal.

All articles