Founders

How to Write a SAFE That Both Sides Understand

Antonio Evans10 min read

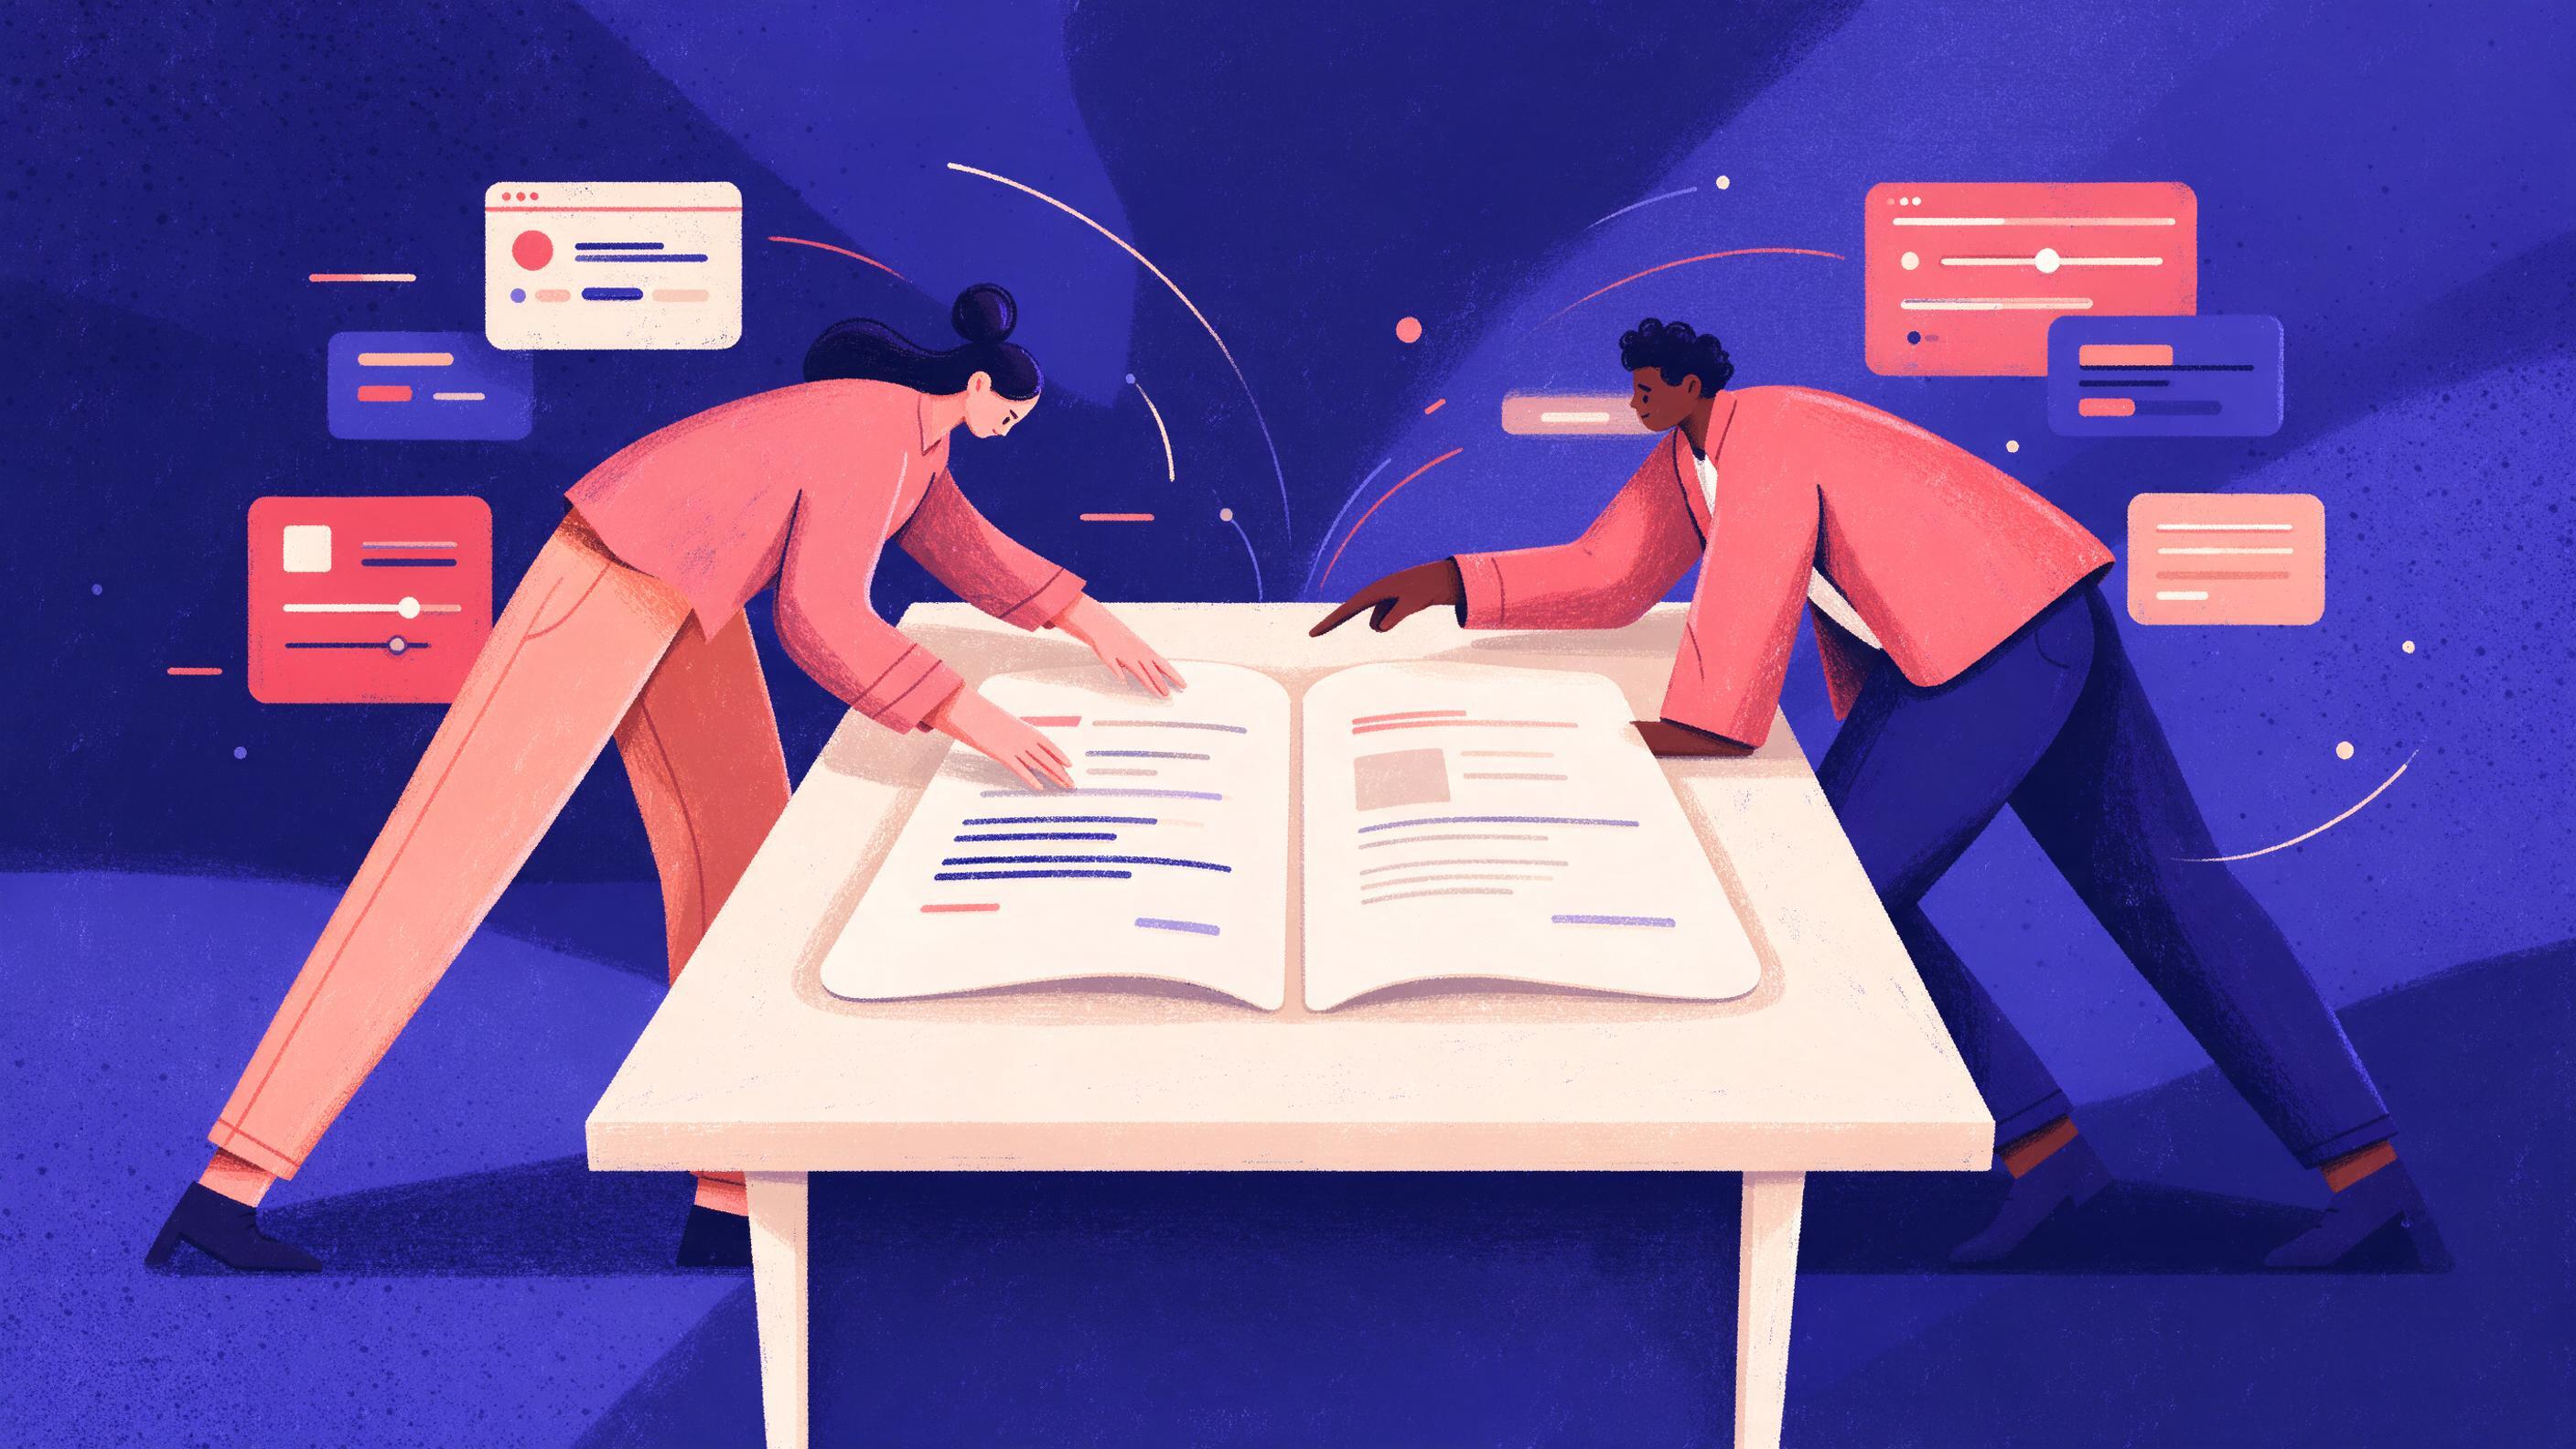
A two-page spread of a SAFE document on a desk, with a founder and an investor leaning over it from opposite sides.
Key points

Key points

  1. 1A post-money SAFE is four economic terms in one short document: valuation cap, discount, pro rata side letter and most favored nation clause.
  2. 2The valuation cap fixes ownership at signing: investment divided by post-money cap, so a $500,000 SAFE on a $5,000,000 cap is 10% before any priced round.
  3. 3Every SAFE you add dilutes founders rather than earlier SAFE holders, which is why you must model the stack before signing, not after.
  4. 4Pro rata and MFN rights are the two clauses that quietly complicate your next priced round, so negotiate their scope and termination date.

Read the SAFE as four economic terms, not one contract

A SAFE (Simple Agreement for Future Equity) is a short contract in which an investor funds your company now in exchange for the right to shares later, converting automatically when you raise a priced round the YC SAFE page. Y Combinator introduced it in 2013 as a cheaper alternative to convertible notes, and it has become the default early-stage instrument in the United States the Warp explainer. Carta notes that pre-seed rounds are almost always raised with convertibles like SAFEs rather than priced equity Carta's pre-seed guide.

The post-money form replaced the earlier pre-money SAFE in 2018, and it changed the math in a way that matters to founders. Under the post-money SAFE, the investor's ownership percentage is fixed at signing and is calculated as the investment amount divided by the post-money valuation cap Avisen Legal. Under the old pre-money form, SAFE holders shared dilution from later SAFEs with the founders. Now, every additional SAFE dollar dilutes the founders, not the existing SAFE investors CRV's SAFE guide.

That single change is why reading the document as one blob is a mistake. The SAFE has a small number of negotiable variables, and each one moves dilution on a different axis at a different time. Treat it as four separate terms and the negotiation becomes simpler: you can concede on one without handing over the whole cap table.
The valuation cap: what you actually sell at signing

The valuation cap is the highest valuation at which a SAFE converts. If your next priced round values the company above the cap, the SAFE converts at the cap, rewarding the early investor the YC SAFE page. Because the post-money cap includes the SAFE investment itself, the ownership you sell is immediately visible to both sides.

The clean way to set it is backward from the raise, not forward from a valuation you like. YC suggests starting from how much you are targeting and how much ownership you are willing to sell, then solving for the cap: a $1M raise selling 15% implies a post-money cap of about $6.7M the YC SAFE page. Raise less on the same cap and you sell less; raise on multiple caps and the ownership adds up.

Here is a worked stack. Founders start at 100% and sign three post-money SAFEs before any priced round:

SAFEInvestmentPost-money capOwnership sold
SAFE 1$500,000$5,000,00010.00%
SAFE 2$500,000$6,000,0008.33%
SAFE 3$1,000,000$8,000,00012.50%
Total$2,000,000mixed30.83%

After those three SAFEs, the founders hold about 69.17% before the priced round and before any option pool expansion, which matches the worked example published by Avisen Legal Avisen Legal. The priced round then dilutes everyone again. This is the decision rule most founders miss: the cap on the last SAFE you sign does not just price that investor, it sets the floor under how much of the company you have left when the Series A lead arrives.

The other failure mode is a cap set far below your expected next-round valuation. If you raise a SAFE at a $5M cap and later price at $10M, the SAFE investor converts at roughly half the price the new investors pay, an effective discount close to 50% the TKNTyson Law guide. That is not a disaster in itself if the money buys real progress, but it should be deliberate. Founders who cap low to close a round often find the Series A lead asking why so much of the company is already gone.

Negotiation points on the cap:

  • Agree the cap as a post-money number and write it that way, never as an ambiguous "valuation."
  • Model the full stack at your expected Series A price before you sign the third SAFE, not after.
  • If an investor will not move on price, move on amount: a smaller check on the same cap sells less ownership.
  • Ask whether the cap should include a discount as well, since a SAFE with both gives the investor whichever produces more shares CRV's SAFE guide.

The discount: a percentage off the next round's price

A discount gives the SAFE holder a lower price per share than the new money in your priced round. On a 20% discount, an investor pays 80% of what the new investors pay, which works out to 25% more shares for the same money CRV's SAFE guide. If the next round prices at $5.00 per share, the SAFE investor converts at $4.00 the TKNTyson Law guide.

Put numbers to it. An investor puts in $100,000 with no cap and a 20% discount, and your Series A prices at $5.00 per share. The investor gets 25,000 shares ($100,000 divided by $4.00) instead of 20,000. At a post-Series-A price of $5.00, that extra 5,000 shares is $25,000 of value, paid for with a 20% concession on price.

Two mechanics decide how much the discount costs you:

  • Cap plus discount. When a SAFE carries both, the investor converts at the lower of the two prices. On a fast-growing company the cap usually binds, so the discount is insurance that costs little. On a flat round the discount binds.
  • Discount only. CRV describes discount-only SAFEs as less common and best suited to situations where setting a valuation still feels premature CRV's SAFE guide. TKNTyson Law notes that many investors refuse a SAFE without a cap unless the startup has unusual leverage the TKNTyson Law guide.

The insight a first search will not give you: a discount is a bet about the shape of your next round, and a cap is a bet about its size. If you expect the valuation to rise sharply, the cap is worth fighting harder on than the discount. If you expect a modest step up, the discount is the term that actually binds, so cap the discount instead (common practice sits in the 10% to 20% range per TKNTyson Law) and leave the cap loose.

Worth knowing from market data: about 72% of SAFEs issued in 2025 used a valuation cap with no discount, making cap-only the dominant structure by a wide margin CRV's SAFE guide. If an investor insists on both, that is a negotiation position, not a market norm.

Negotiation points on the discount:

  • Ask whether the cap or the discount binds at your expected round size, and put the answer in writing in your model.
  • Cap the discount percentage rather than accepting an open-ended "market discount."
  • Refuse a discount that runs past the first priced round; a discount that survives multiple rounds compounds against you.

The pro rata side letter: a right to buy more, not a promise

Pro rata rights live outside the SAFE, in an optional standardized side letter, and give the investor the right (not the obligation) to buy shares in the next priced round to maintain their percentage the YC SAFE page. The side letter is a short document that points back to the SAFE and defines the pro rata share as the shares issued on conversion divided by company capitalization just before the financing the line-by-line side letter explainer.

The mechanical problem is allocation. A Series A lead typically wants to own a meaningful percentage, and your check size for the round is finite. If several small SAFE holders each hold pro rata, they can consume allocation the lead expected to fill, which complicates closing. CRV calls this out directly and recommends limiting pro rata to the largest check writers and restricting it to the next round only CRV's SAFE guide.

A worked example makes the squeeze concrete. Say your Series A is $6M and the lead wants 18% post-money, with 30.83% of the company already sold to SAFE holders from the table above. If all three SAFE holders exercise full pro rata, they jointly put in roughly $1.85M of the round (30.83% of the post-money pie, apportioned against the new money). The lead now has $4.15M to deploy against an 18% target and either asks for a lower price, asks you to shrink the round, or walks. You have not lost the round, but you have lost leverage at exactly the moment you need it.

The side letter also terminates on defined events, typically the initial closing of the equity financing, a liquidity event or a dissolution event the line-by-line side letter explainer. Read that termination clause closely: a pro rata that survives into a second round is a different, much more expensive right.

Negotiation points on pro rata:

  • Give it only to investors above a check-size threshold, and write the threshold down.
  • Restrict it to the next priced round, with automatic termination at that closing.
  • Require the investor to exercise within a fixed window (commonly a short notice period) before the allocation is released.
  • Exclude it from MFN SAFEs unless the investor is paying for it with a larger check.

The most favored nation clause: the term that follows you

An MFN SAFE has no cap and no discount. Instead, it automatically takes the cap or discount of any SAFE you issue later, so the investor can put money in now without deciding those terms the YC SAFE page. It is meant for a short bridge from trusted investors when a priced round is near, and it turns into a trap when the bridge gets long.

The trap has a specific shape: every concession you make to a later SAFE is automatically extended to every MFN holder. CRV states the tradeoff plainly: one concession can affect all MFN holders, which reduces your flexibility in later SAFE negotiations CRV's SAFE guide.

Run the numbers. You raise $250,000 on an MFN SAFE early. Eight months later you raise $750,000 at a $6,000,000 post-money cap. The MFN investor now adopts that $6M cap and converts at $250,000 divided by $6,000,000, about 4.17%. Fine. But if a later angel negotiates a $4,000,000 cap, the MFN investor adopts that too, converting at about 6.25%. You have effectively given the earliest investor the best price of the whole round, retroactively.

Negotiation points on MFN:

  • Put a floor or a defined reference set on the MFN: it adopts terms from SAFEs issued within a stated window, not forever.
  • Write in that the MFN does not pick up pro rata rights or side letters, only the economic terms.
  • Set an expiry: if no priced round closes by a certain date or the MFN SAFE's amount is small, the clause lapses.
  • Never issue an MFN alongside a round where you expect to negotiate several different caps, because the best cap propagates to every MFN holder.

A clause-by-clause checklist before you sign

The document is short enough to review in one sitting if you know what to look for. Use this as the pre-signature pass, and have a lawyer confirm anything you are unsure about; standardized does not mean legal advice is optional the TKNTyson Law guide.

ClauseWhat to checkFounder risk if missed
Valuation capPost-money, written as a number, modeled against expected Series A priceOversells the company before the priced round
DiscountPercentage, whether cap or discount binds, stops at first priced roundCompounds against you across rounds
Pro rata side letterThreshold, next round only, notice window, termination eventsEats the lead's allocation and your leverage
MFNReference window, economic terms only, lapse conditionLater concessions propagate retroactively to early holders
Conversion triggerDefined as a priced round; understand acquisition and dissolution treatmentSurprise conversion or payout outcomes
Side letter referencesCorrect SAFE type cited in the side letterAmbiguity that needs a lawyer to unwind

The arithmetic you must be able to run yourself is simple enough to keep in a spreadsheet:

ownership_sold = investment / post_money_cap
founder_remaining_before_round = 1 - sum(ownership_sold for each SAFE)
post_round_founder = founder_remaining_before_round * (1 - new_money_pct - pool_pct)

If that last line starts to look thin, you are not negotiating a SAFE anymore, you are negotiating whether you will still be a meaningful owner at Series A. That is the moment to stop signing and start modeling.

Carta's guidance is to decide, before you raise, how much equity you plan to give up, how much you want the next priced round to be and what milestones the SAFE money buys Carta's SAFE explainer. Those three answers drive every clause above.

What the post-money form means for your cap table

Post-money SAFEs are the market default, and most investors will expect one unless you negotiate something else Avisen Legal. The practical implication is that you should build the cap table forward, SAFE by SAFE, at a fully diluted post-conversion basis rather than eyeballing it.

The reason is structural. Under the post-money form, subsequent SAFEs dilute founders, not earlier SAFE holders Avisen Legal. Stacking three or four post-money SAFEs without a model is one of the more common ways founders reach a Series A with less ownership than they expected Avisen Legal. That is not a hypothetical: the 30.83% figure in the table above is the arithmetic of three ordinary SAFEs, not an extreme case.

Two habits keep this under control. First, keep the cap table in one place with each SAFE's amount, cap and implied percentage, and update it the day you sign rather than the day you close. Second, review the SAFE stack monthly in the boring way: ask what each clause would do if the next round priced at, above and below the last cap. The clause that hurts you is usually the one you did not model, and it is almost always pro rata or MFN.

When you are raising the priced round itself, the work becomes a pipeline problem: a target list, staged meetings and a weekly review, run like a sales process rather than a series of one-off conversations startupfundraising.com. The SAFE stack is the input to that process, and the cleaner the stack, the simpler the diligence conversation.

If you would rather not model the cap table alone, a short working session with someone who has seen hundreds of SAFE stacks can save an expensive mistake; Quanta's consulting team offers a free 30-minute discovery call to look at your goals and give a tailored recommendation Quanta Consulting.

FAQ

FAQ

What is the difference between a pre-money and a post-money SAFE?

A pre-money SAFE calculates the investor's ownership against the company's valuation before the SAFE and other convertibles are accounted for, so later SAFEs dilute earlier SAFE holders as well as founders. A post-money SAFE fixes the investor's percentage at signing as the investment amount divided by the post-money cap, so subsequent SAFEs dilute founders only Avisen Legal.

If a SAFE has both a cap and a discount, which one applies?

The investor gets the conversion price that produces more shares, which is the lower of the cap price and the discounted price. On a fast-rising valuation the cap usually binds; on a modest round the discount can bind CRV's SAFE guide.

Should I give every SAFE investor pro rata rights?

No. Pro rata can consume the allocation your Series A lead expected to fill, so the common safeguard is to limit it to the largest check writers and restrict it to the next round only CRV's SAFE guide. The side letter automatically terminates at the equity financing closing, a liquidity event or a dissolution event the line-by-line side letter explainer.

What does an MFN clause actually commit me to?

It commits you to giving that investor the benefit of any better cap or discount you issue to a later SAFE investor before the priced round. Every concession can therefore affect all MFN holders, which is why the clause works best as a short bridge and needs a reference window or expiry CRV's SAFE guide.

How do I calculate how much of my company a SAFE sells?

Divide the investment amount by the post-money cap. A $500,000 SAFE on a $5,000,000 post-money cap sells 10%, and a $1,000,000 SAFE on an $8,000,000 cap sells 12.5% Avisen Legal. Add up every SAFE in the stack before you sign another one, since each new SAFE dilutes founders rather than earlier SAFE holders the YC SAFE page.

Sources

Sources

  1. The SAFE
  2. Y Combinator SAFE Explained: Terms, Mechanics & Dilution - Warp
  3. Pre-Seed Funding: A Startup's Guide to Early-Stage Fundraising - Carta
  4. Pre-money vs. Post-money SAFEs Explained
  5. SAFE Agreements for Startups (2026 Guide)
  6. The Ultimate Guide to SAFEs for Startups
  7. Post Money SAFE Pro Rata Side Letter Explained Line by ...
  8. What is a SAFE? (Simple Agreement for Future Equity) - Carta
  9. Investor Pipeline: Build, Prioritize, Run Your Fundraise
About the author

About the author

Antonio Evans
Antonio Evans

Antonio Evans is the founder of Quanta Intelligence and a fractional CTO who builds HIPAA-ready AI systems for health and life-science companies. Before that he was technical co-founder of FriendsEAT for twenty years, CEO of Socialdraft, and a data engineer at IBM. Antonio lives with his dog Santino in Lisbon, Portugal.

All articles