Fintech

How to Choose a Payment Provider Without Lock-In

Antonio Evans9 min read

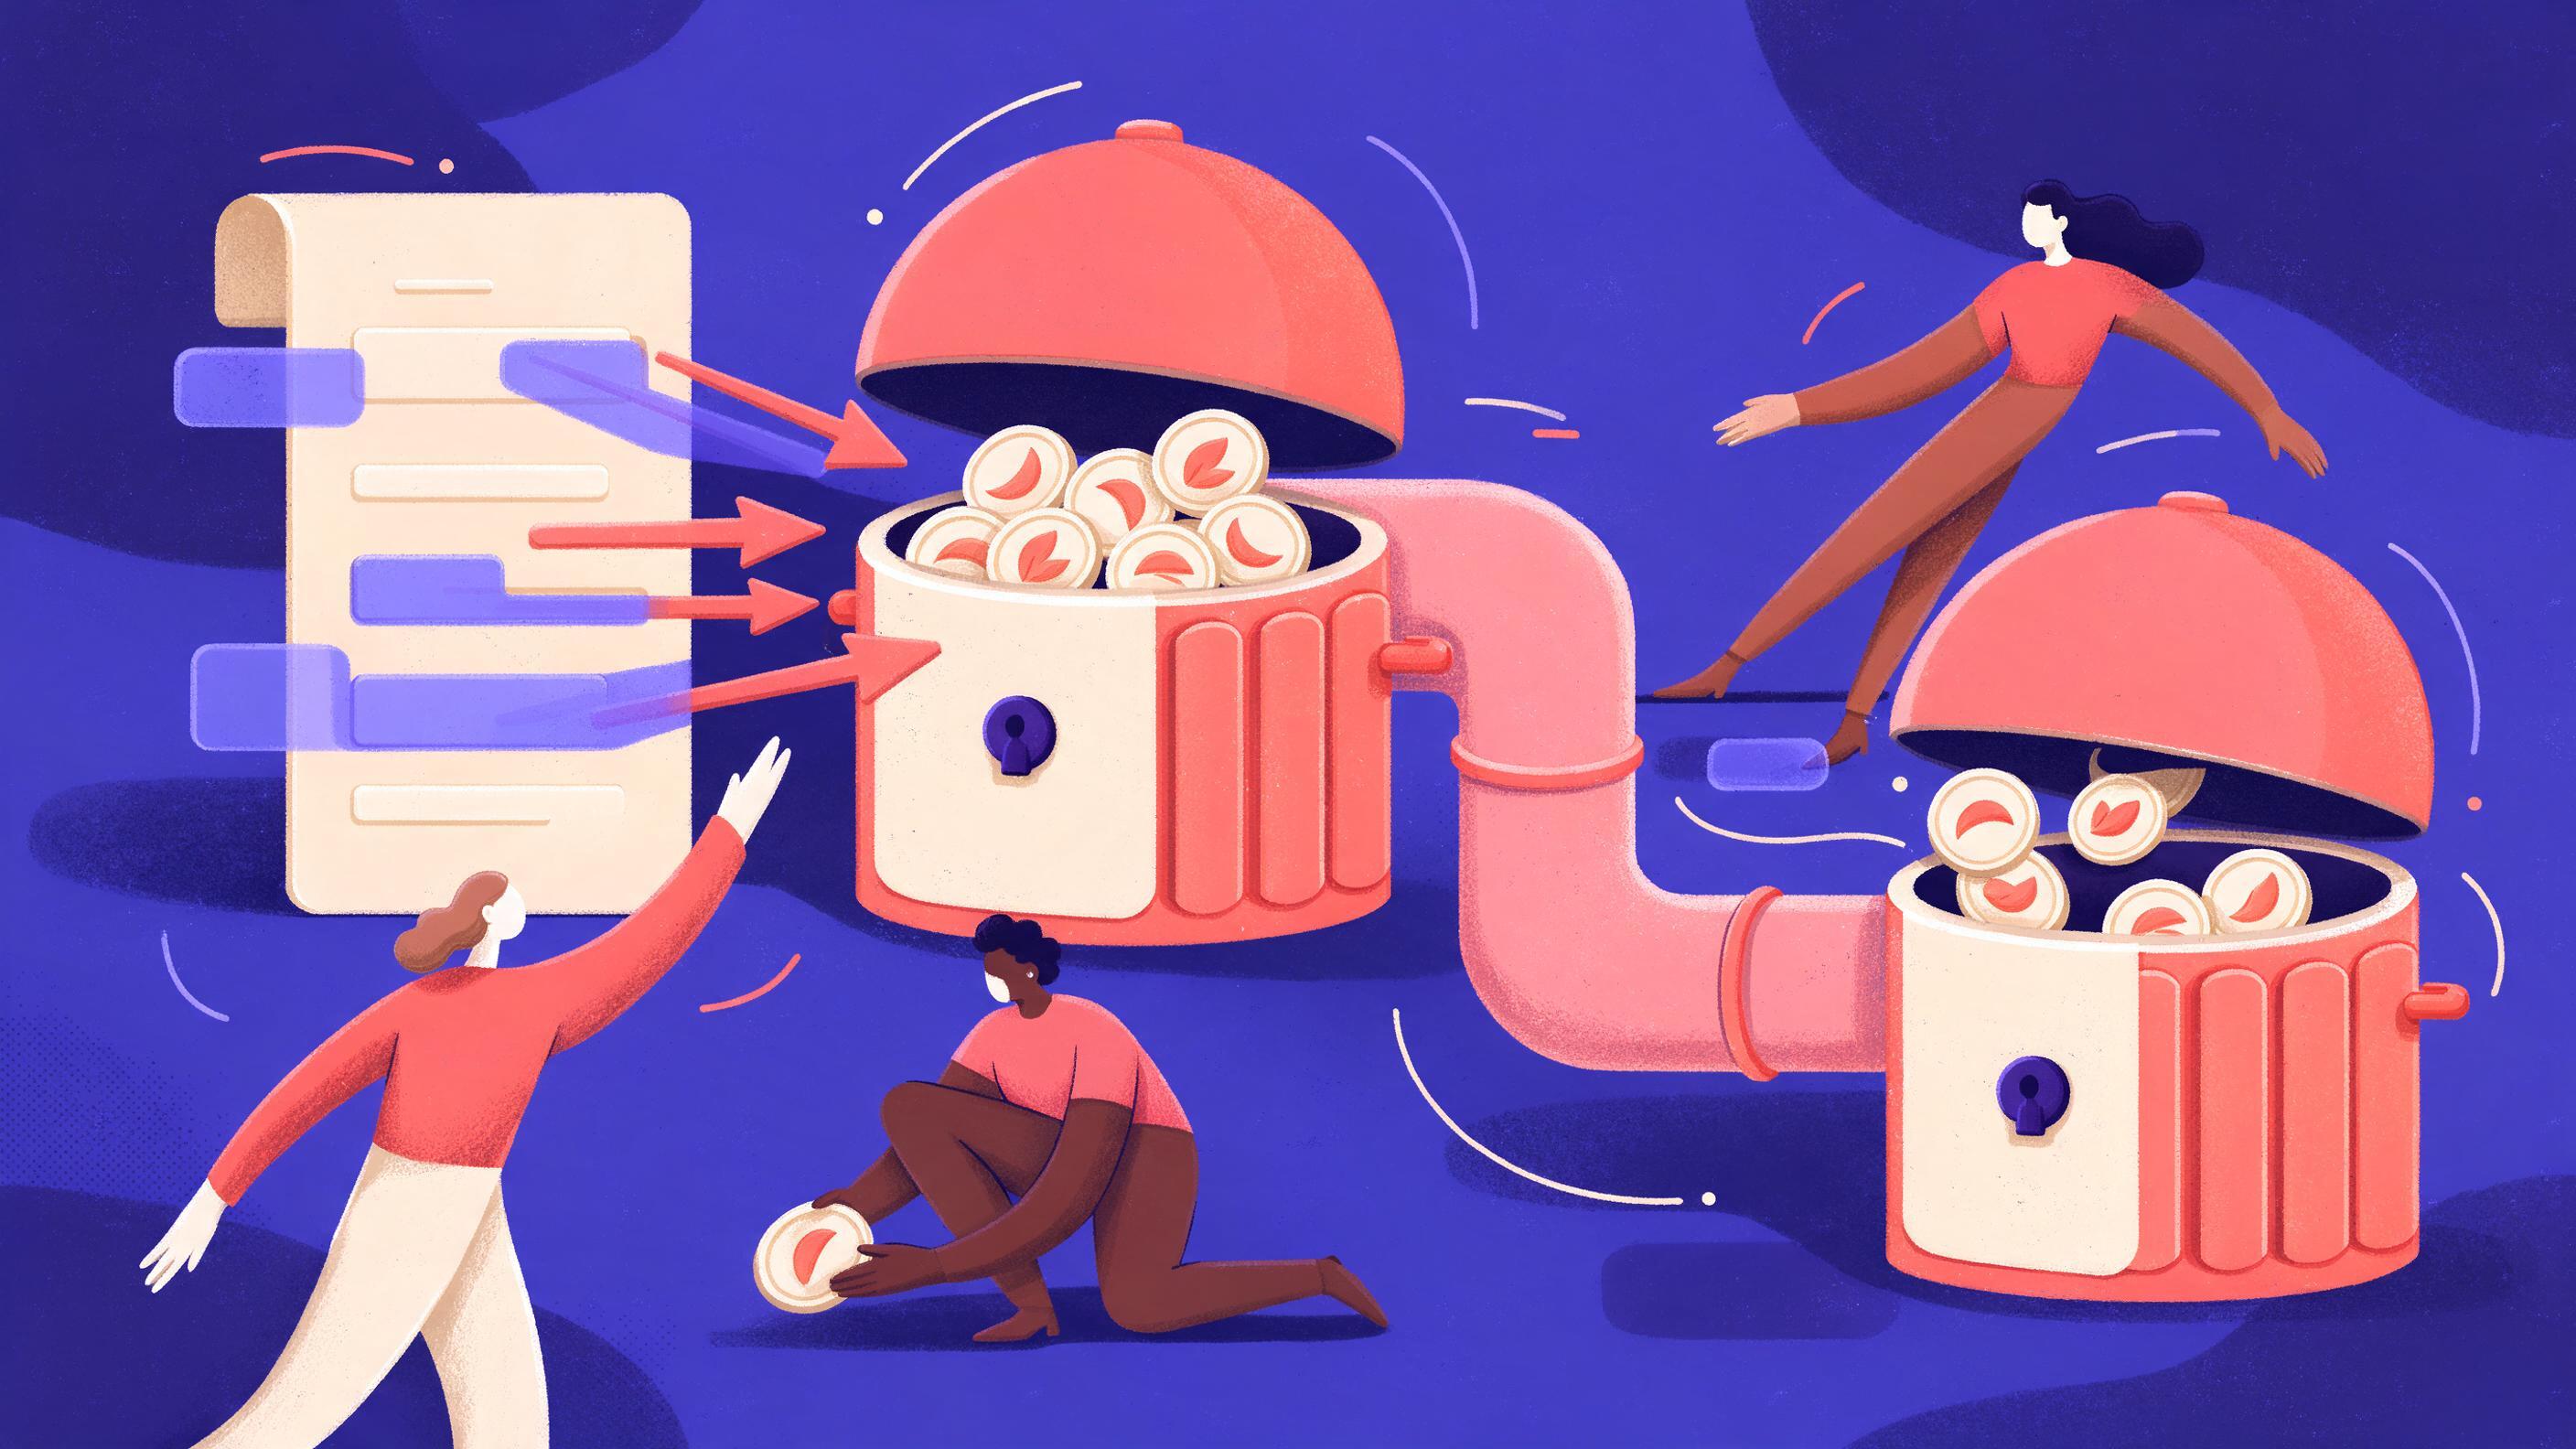
A split scene: on the left, a contract document with several clauses highlighted and arrows pointing to a vault labeled 'payment tokens'; on the right, the same tokens moving through a pipe into a second vault.
Key points

Key points

  1. 1Card tokens are not automatically portable, so ask in writing who controls the vault and the mapping behind each token.
  2. 2Price the exit before you sign: a migration plan with a dual-running period, a named termination-assistance clause, and a data return deadline.
  3. 3Interchange is set by the card networks and dominates card processing cost, so switching purely for a better rate has a low ceiling.
  4. 4If the provider will not commit to portability terms, treat the missing terms as a switching fee you will pay later.

Who actually owns the payment credential

Start with the architecture, because lock-in lives in it. In a card payment, the customer's bank (the issuer) approves or declines, and the merchant's bank (the acquirer) collects the money on the merchant's behalf, connected through a card network such as Visa or Mastercard (Stripe on acquirer vs issuer). The acquirer maintains the merchant account that receives funds and assists the merchant with chargeback management, while the processor transmits the transaction (Global Blue on the acquirer role).

That division matters for exit planning. Leaving one component does not necessarily mean leaving the others. You can keep your acquiring bank and change your gateway, or keep the gateway and move processing, if the pieces are separable. All-in-one bundles are convenient, but a bundled gateway, processor and acquirer can make switching harder because you have to replace the whole stack at once, which is the point an independent gateway vendor makes about all-in-one solutions (FreedomPay). The first decision rule: know which of the layers you are actually buying, and insist the contract names them separately.

The less visible layer is tokenization. When a customer saves a card, your provider swaps the card number (the PAN) for a token, and only the original tokenization system can exchange that token back for the PAN when a payment is authorized (Payabli tokenization docs). That sentence is the whole lock-in story. If your stored tokens only resolve inside one processor's vault, a new processor cannot charge them, and every saved card becomes a re-collection problem.
Three kinds of tokens, three different exit costs

Not every token behaves the same. Traditional payment tokens are generated by a gateway or processor and resolve only in that provider's systems, which makes them easy to manage but hard to move (Payabli tokenization docs). Device tokens are tied to a phone or watch's secure element and are used by Apple Pay, Google Pay and Samsung Pay (Payabli tokenization docs). Network tokens are issued and managed by the card networks themselves, so they can be updated automatically when a card expires or is reissued, but they are provisioned through a token service provider and constrained by domain controls that limit where they can be used (Very Good Security on network tokens).

The practical test is not "do you support tokens?" It is "who is the Token Requester, and do my tokens survive if I move?" A network token is more portable in principle, but only if the token requester relationship is under your control or transferable, and only if the destination processor can accept it (Very Good Security). The blunt version of this argument comes from a payments consultant: the real asset is not the token string but the mapping behind it, and if the provider controls the mapping and your only access is through its API, contractual claims that you own your data mean little (Payments Therapist).

Token typeWho issues itResolves outside original provider?Typical migration cost
Processor or gateway tokenYour processor or gatewayNo, unless exported as a vault fileHigh: re-collection or assisted migration
Device tokenApple, Google or Samsung walletTied to the deviceLow to medium: customer re-enrols once
Network tokenCard network via a token service providerSometimes, if requester moves and destination supports itMedium: depends on requester control
Bank mandate (ACH or direct debit)Your bank or the mandate holderDepends on mandate ownershipMedium to high: customers re-authorize

Bank mandates deserve their own line in the table because they are often forgotten. Direct debit and ACH authorizations live with whichever entity holds the mandate, so they can be harder to reassign than tokens, and that is a separate question to put to the provider.

Price the exit before you price the rate

Most provider comparisons concentrate on processing cost. That is worth doing, but it understates the stake for two reasons. First, interchange, the fee the acquirer pays the issuer, typically runs roughly 1.4% to 2.5% of the transaction amount plus a fixed fee for US credit cards, and it is set by the card networks, not your processor, so a new processor cannot negotiate it away (NMI on interchange). Second, US businesses paid about $187.2 billion in card processing fees, of which interchange was 70% to 90%, leaving a comparatively small slice for the parts a provider actually controls (Stripe on interchange). A migration undertaken purely to shave processor markup has a low ceiling. A migration undertaken to escape non-portable tokens or an unhelpful contract has a much higher ceiling.

A worked estimate, using round numbers you should replace with your own: suppose you hold 40,000 stored cards and 12% of them are charged in any given month. That is 4,800 saved-card charges monthly. If the new provider cannot accept the old tokens, each customer has to re-enter card details, and saved-card charges fall for a while. Assume 35% of that traffic is lost or delayed in the first two months and average saved-card value is $45. Lost gross volume is 4,800 × $45 × 0.35 × 2 = $151,200. At a 3% all-in cost, the avoided processing cost on that volume is about $4,500, but the revenue loss is the real number, and it dwarfs it. Add engineering time at, say, 120 hours, plus a dual-running period where two providers charge fees on overlapping volume. The point of the exercise is not precision. It is to show that token portability is often a revenue question, not a fee question.

Interchange rates vary by card type, channel and region, and regulated markets cap them, so any savings case has to be built on your actual card mix rather than a headline rate (NMI on interchange). Where the transaction lands matters too: authorization, clearing and settlement are separate stages, and settlement timing affects your cash flow during a migration (concryt on authorization, clearing and settlement).

The contract clauses that hide a switching fee

Vendor lock-in in subscription software rarely comes from one clause. It accumulates from proprietary formats, auto-renewal windows, vague export obligations, API extraction limits, and deep workflow integration, and the same pattern applies to payment agreements (toslawyer on SaaS lock-in). Look for these, in order of how much they cost you later:

  • Termination for convenience. Without it, you can leave only by proving breach, and the usual fallback is a cap on early termination fees that should decrease over the term (toslawyer).
  • Transition assistance. A named period, typically at least 90 days, with read-only data access, export support and cooperation with the new provider, priced at a stated rate so it cannot be repriced during departure (toslawyer).
  • Data return specification. Not "we will return your data" but which tables, which fields, which format, which deadline.
  • Deletion and certification. A stated window, usually 30 to 60 days, with written certification of destruction, which matters if you handle personal data (toslawyer).
  • Token and mandate portability. The clause that names what happens to stored credentials, whether export includes vault data, and who pays for reprovisioning.
  • Auto-renewal notice. A short cancellation window is a switching fee collected in advance.

Two structural clauses also change what exit costs, and they are easy to miss. If your provider is a merchant of record, it is the legal seller, absorbing tax registration and remittance, fraud liability and much of the compliance scope, so leaving may mean standing up obligations you never had to run (Stripe on merchant of record vs payment facilitator). If it is a payment facilitator, it aggregates sub-merchants under its own infrastructure, so your account exists under its umbrella rather than directly with an acquirer (Paddle on payfac vs merchant of record). Ask which model you are on, because it determines whether you can take your merchant account with you. A payfac shortens onboarding precisely because it has already done the heavy lifting with banks, and the sub-merchant inherits that infrastructure instead of owning it (Stripe on processor vs payfac).

A checklist to ask before signing

Work through this with the provider and get answers in the contract, not in a call.

AreaQuestionWhat a good answer looks like
Token ownershipWho is the Token Requester for network tokens?You, or transferable on notice
Token exportIs a vault export available, in what format and deadline?Named format, stated days, stated cost
Mapping accessCan we resolve our own tokens if we leave?Yes, under defined security controls
MandatesWho holds ACH and direct debit mandates?You or a transferable arrangement
Data returnWhich tables and fields come back, and when?Specified, with a deadline
Transition helpIs there a named assistance period and rate?Stated period and stated price
TerminationCan we leave without proving breach?Termination for convenience with notice
FeesWhich fees survive termination?Listed, capped, declining
DeletionWhen is data destroyed, with certification?Stated window and written proof
RenegotiationAre rate changes capped during the term?Capped or indexed

The minimum acceptable bundle, if you want a single decision rule, is three things: a token export commitment, a transition assistance period with cooperation duties, and a data return deadline. Anything less is a switching fee you have not been shown yet.

What a realistic migration looks like

A migration that preserves saved cards usually runs four phases. First, inventory: count stored credentials by type (processor tokens, network tokens, device tokens, mandates) and map which ones cannot move. Second, export and reprovision: obtain the vault export or have the destination provider provision its own tokens, which for network tokens means a new token requester relationship (Very Good Security). Third, dual running: route a rising share of traffic to the new provider while the old one remains available, watching authorization rates and declines. Fourth, cutover and cleanup: close the old account, confirm the data return is complete, and get the deletion certificate.

The risk to watch is that network token coverage is uneven by region and issuer, so a PAN fallback stays necessary and must be kept current (Very Good Security). Many failures happen at authorization, where expired or invalid card details, insufficient funds and fraud blocks stop a sale before clearing ever begins, so a circuit-breaker that falls back to the old provider during peak hours is cheap insurance (concryt).

This is also where a second pair of hands helps. Running the inventory and the migration scripts, or comparing candidate providers against your token inventory and settlement needs, is work an AI expert can take on and hand back as a finished deliverable, and Quanta Intelligence's experts are built for exactly that kind of context-heavy task. If you would rather test candidate processors against your own data first, you can reach text, embedding and other models for the analysis through Quanta Inference.

Decision rules that survive the negotiation

Three rules cover most of the judgment calls. First, separate the layers: buy gateway, processor and acquiring separately where the volumes justify it, and prefer architecture where the gateway does not move money, because that keeps processor and acquirer choices open (FreedomPay). Second, prefer payfac convenience early and independent acquiring later, since a payfac shortens onboarding but leaves your account under someone else's umbrella (Paddle). Third, treat the contract as the technical architecture: a portability sentence you can enforce is worth more than a features page.

One more insight that most comparisons miss. The four-party model means your customer relationship is with the issuer, not the processor, and the acquirer is the party that actually recovers the funds and supports chargeback handling (Global Blue on the acquirer role). So switching processors is not a rebranding exercise; it is a change in who carries settlement and dispute duties for you. Put that in your exit estimate too.

FAQ

FAQ

Are card tokens portable between processors?

Usually not by default. Traditional tokens are generated by a provider and only resolve inside its systems, so a different processor cannot charge them without an export or reprovisioning step (Payabli). Network tokens are more transferable in principle, but only if the token requester relationship is yours or can be moved (Very Good Security).

What data should I get back when I terminate?

The returned data should include stored credentials where they can legally be exported, transaction history with fees and reference numbers, customer and mandate records, and dispute files. The contract should specify fields, format and a deadline, not leave format to the provider's discretion (toslawyer).

How long should a migration take?

Plan around a named transition assistance period of at least 90 days for data access and cooperation, and add your own dual-running window on top (toslawyer). Actual cutover depends on how many credential types need reprovisioning and on settlement timing at the new provider (concryt).

Is switching to a cheaper processor worth it?

Often not on rate alone. Interchange is set by the networks and makes up most of card processing cost, so the controllable slice is smaller than headline comparisons suggest (Stripe, NMI). Switching is strongest when it unlocks portability, better authorization outcomes, or terms you could not get otherwise.

What if the provider refuses portability terms?

Treat the refusal as a disclosed switching cost and price it into the deal, or insist on termination for convenience with a capped, declining fee (toslawyer). Also confirm whether you are on a merchant of record or payfac model, since that decides whether your merchant account can leave with you (Stripe).

Sources

Sources

  1. Acquirer vs. Issuer: What's The Difference? | Stripe
  2. Payment Decoded - What is an Acquirer and Why They Are ...
  3. Payment Gateway vs. Processor vs. Acquirer: Key Differences Explained
  4. Payment method tokenization
  5. What Merchants Need to Know About Network Tokens
  6. Everybody Loves Tokenization Until They Try to Leave ...
  7. Interchange Fees Explained: What They Are and How They Work | NMI
  8. Interchange Fees 101: What They Are And How They Work - Stripe
  9. Understanding Payment Authorization, Clearing, and Settlement - concryt.io
  10. SaaS Vendor Lock-In: Exit Clauses and Data Portability ...
  11. Merchant of Record vs Payment Facilitator: A Guide For Business
  12. Payfac vs Merchant of Record - Paddle
  13. Payment Processor vs. Payment Facilitator - Stripe
About the author

About the author

Antonio Evans
Antonio Evans

Antonio Evans is the founder of Quanta Intelligence and a fractional CTO who builds HIPAA-ready AI systems for health and life-science companies. Before that he was technical co-founder of FriendsEAT for twenty years, CEO of Socialdraft, and a data engineer at IBM. Antonio lives with his dog Santino in Lisbon, Portugal.

All articles