Marketing

How to Design a Referral Reward That Does Not Attract Fraudsters

Antonio Evans11 min read

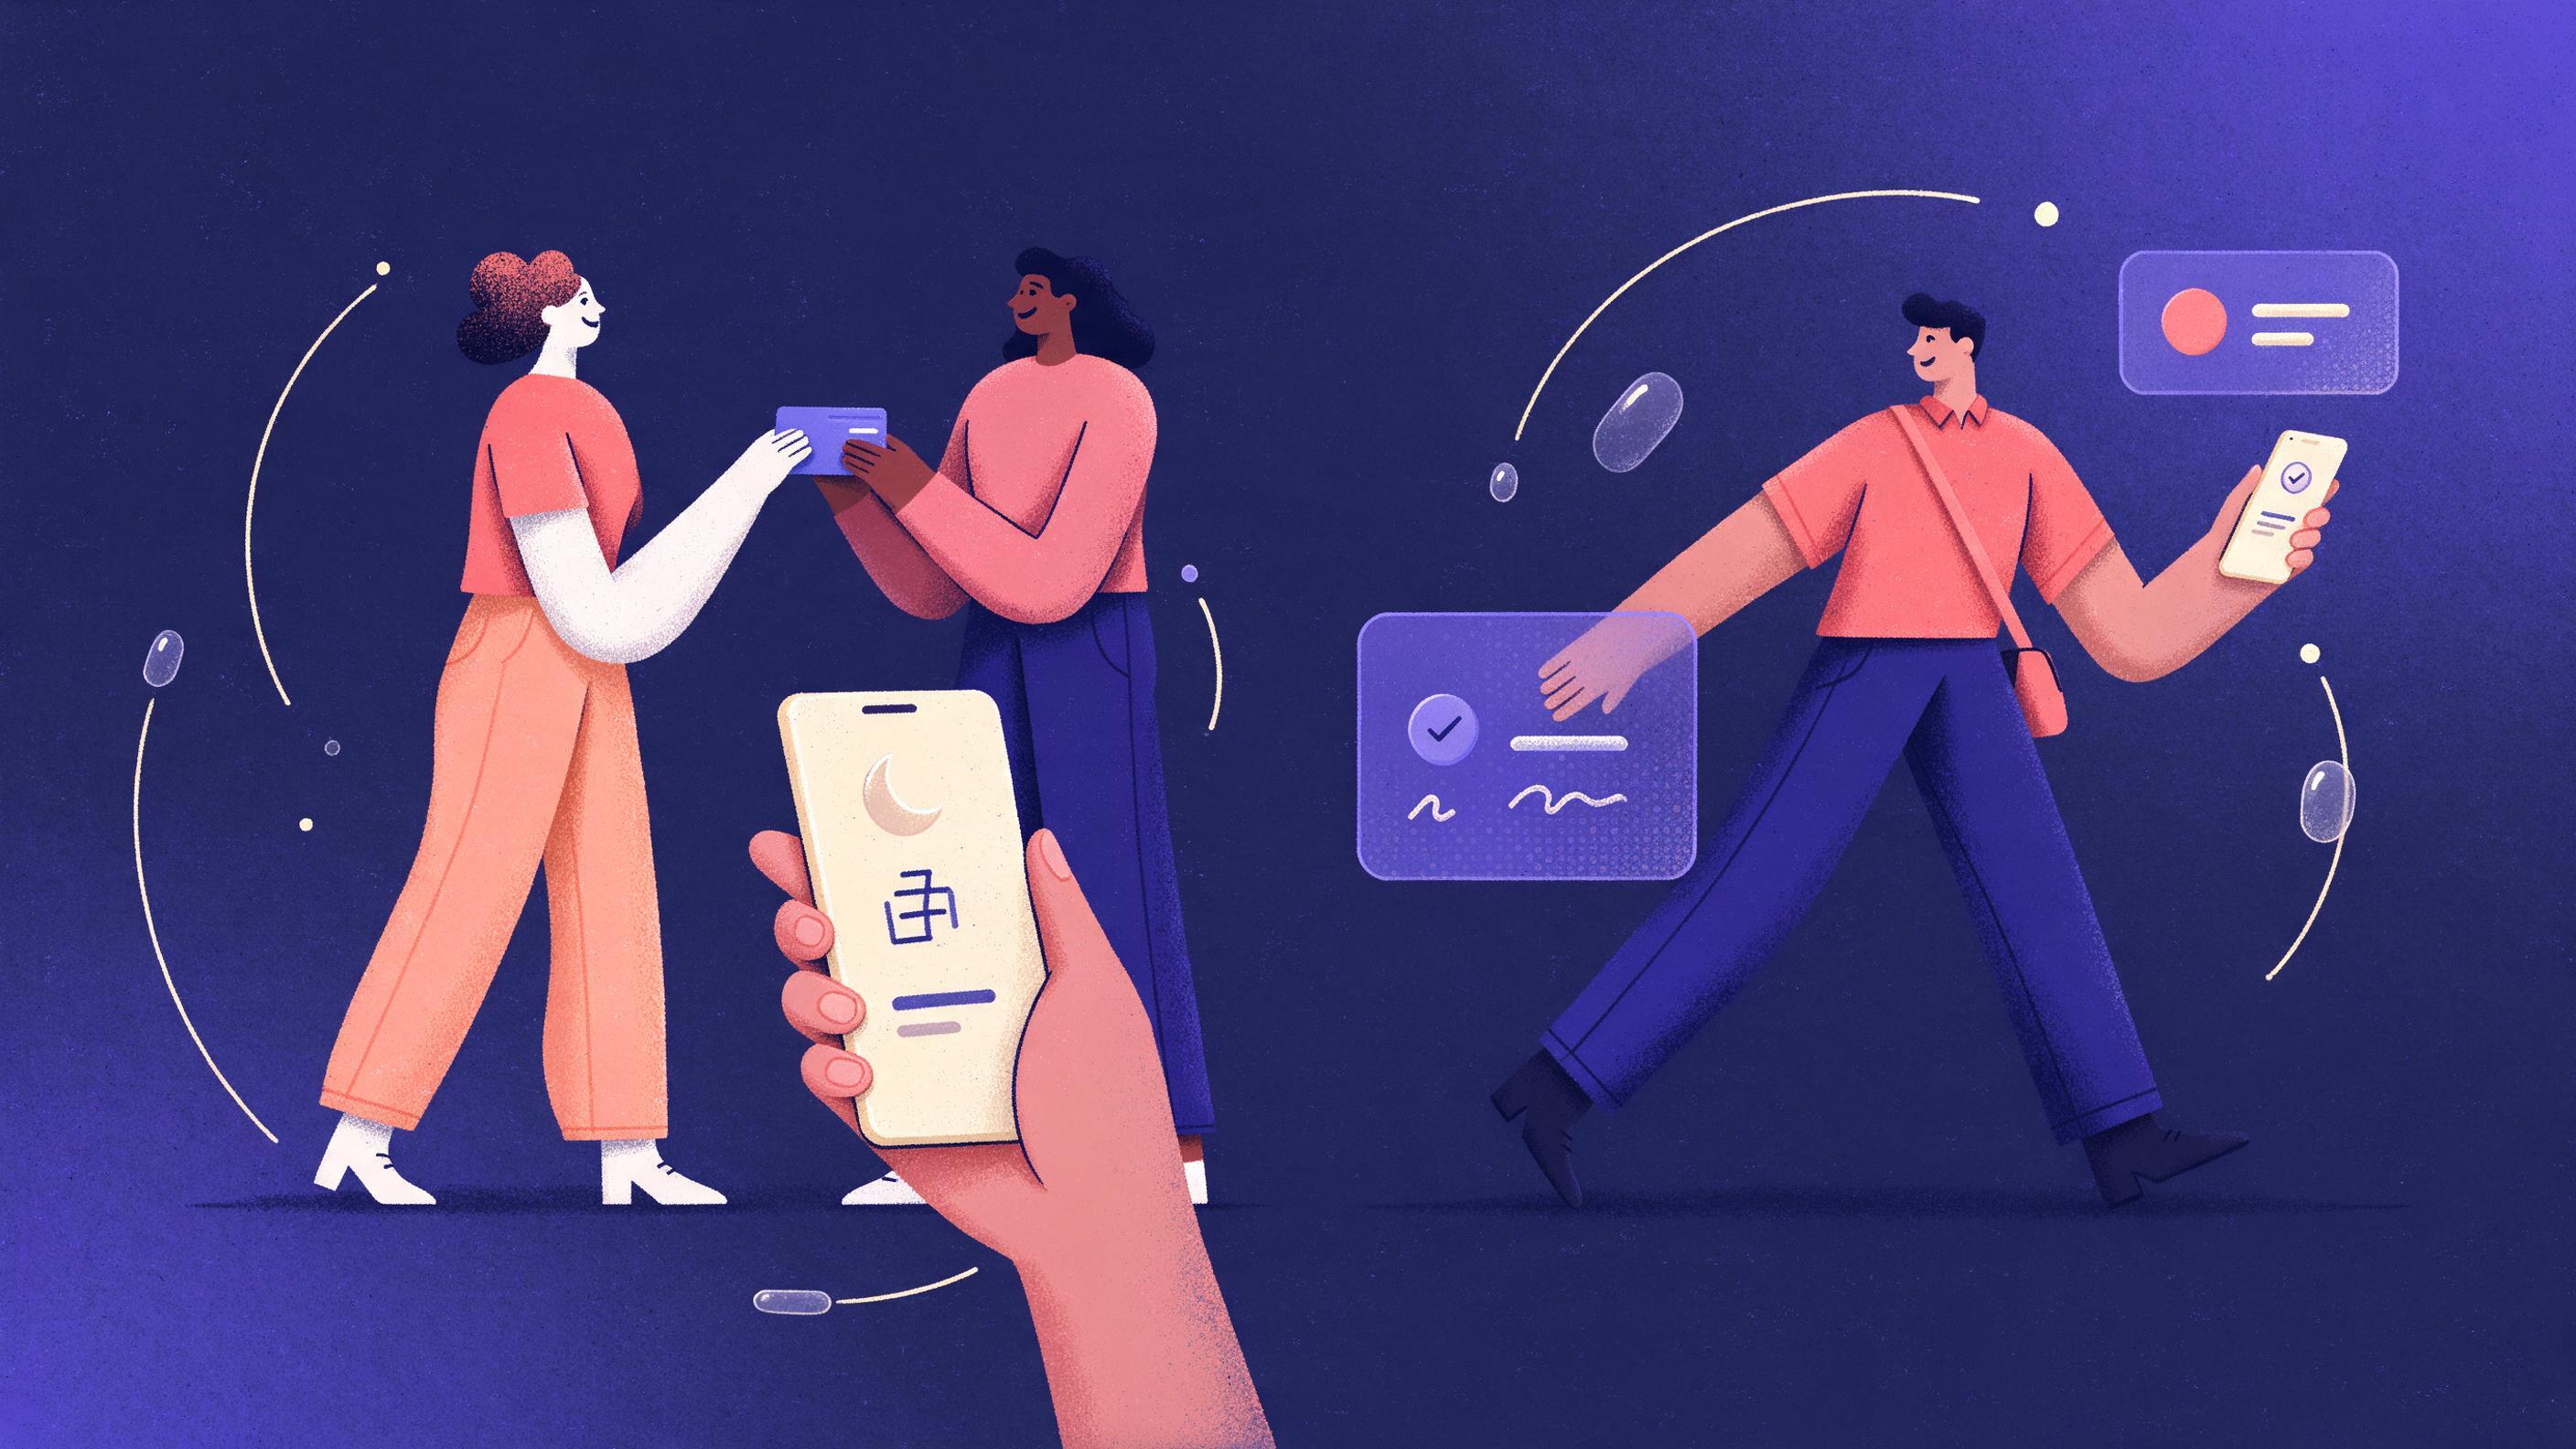
A split scene: on the left, an honest customer hands a friend a referral card and receives a small credit on their phone; on the right.
Key points

Key points

  1. 1A referral reward should cost the fraudster more to fake than it pays, which usually means a modest credit or non-cash perk rather than cash.
  2. 2The reward should vest only after the referred customer's first paid order clears the return window, so refunds and chargebacks surface before money leaves.
  3. 3Duplicate detection on phone, device, payment method, and shipping address catches most self-referral before a payout is approved.
  4. 4Written clawback and account-cancellation terms do more to deter fraud than any single detection rule.

Start from the abuse economics, not the reward catalog

Most referral program guides begin with incentives: cash back, credits, gift cards, free months. That is the wrong end. A fraudster runs a simple calculation. How much does one fake referral cost me in effort and materials, and how much does it pay? Your job is to make that ratio unattractive before you pick a font for the banner.

A common referral fraud scheme works like this: the fraudster creates a main account, makes duplicate accounts, refers them, and then either cashes out rewards or buys discounted product with stolen payment information per Unit21's referral fraud overview. The same source notes that programs rewarding both sides are especially attractive, because one fake signup can yield two payouts.

Do the arithmetic for your own program before launch. Write down four numbers:

  1. The reward value paid per side (or both sides).
  2. The fraudster's cost to create one plausible account: a working email, a phone number, a device or IP profile, and a payment method if a purchase is required.
  3. The minimum qualifying purchase you require, and its refund window.
  4. Your cost to review and reverse one payout, including support time and any chargeback fee.

If the reward exceeds the cost of faking a qualifying purchase, your program is a profit center for the wrong person. The design rule that follows is simple: reward amounts should sit comfortably below the total cost of producing one verified new customer, and qualification should be tied to revenue, not to signups or link clicks. Referral Factory's guidance makes the same point directly: reward the moment a referred lead becomes a customer, not the moment a link is clicked, because that single choice removes most of the incentive to cheat per Referral Factory's fraud video.

That reframe matters because it changes what you are buying. Reward-at-click pays for traffic. Reward-at-revenue pays for customers. Only one of those has a margin attached.
Choose the reward type that is hard to cash out

Reward type decides who your program attracts. Cash and cash-equivalent rewards (bank transfers, prepaid cards) are the most liquid, which makes them the most attractive to a fraudster and the least recoverable once paid. Credits locked to your own product are far less useful to someone who never intended to buy anything twice.

The evidence on which rewards work for honest customers is not that they must be cash. Double-sided programs, where both the referrer and the friend get something, consistently outperform one-sided ones, and the strongest version gives the friend a real reason to buy: a discount, a free product, or credit applied at checkout per Referral Rock's reward guide. Referral Factory reports that over 90 percent of the referral programs run on its platform are double-sided, because reciprocity makes the ask feel like a gift rather than a sales pitch per Referral Factory's double-sided explainer.

You can be double-sided without being liquid. Compare the options:

Reward typeFraudster appealCost to youBest fitWatch out for
Cash or prepaid cardHigh, immediately usable anywhereFull face value, hard to reverseHigh-ticket, infrequent purchasesPayout speed becomes your biggest risk
Store creditMedium, only useful if they buy againFace value less breakageFrequent, low-ticket purchasesNeeds minimum order rules to avoid near-free redemptions
Percentage discountLow, requires a real purchase to matterMargin only, not cashSubscription and repeat purchaseDeep discounts can be gamed with tiny orders
Free product or swagLowYour landed costConsumer brands with physical goodsShipping cost per unit adds up
Free month or upgradeLow to mediumMarginal cost of serviceSaaS and digital productsStacked redemptions on stacked fake accounts

A gift card to another business is a reasonable middle ground for B2B, where the referred company's reward can sit outside your own service model, a pattern Impact's brand guidance recommends because it lowers financial exposure per referral per Impact's fraud-proof design guide. The general principle from Impact is to offer incentives that stay profitable in the short term, so even a fraudulent payout does not put you underwater.

One practical rule: if the reward is fully usable on a zero-cost order, fraudsters will find it. Set a minimum order value greater than the reward, or make the credit expire in a defined window.

Size the reward against margin, then cap it

Reward size is a margin decision, not a marketing one. The Wharton study of roughly 10,000 customers at a German bank found that referred customers were worth at least 16 percent more than non-referred customers with similar demographics, driven mostly by higher retention that persisted over time per Schmitt, Skiera and Van den Bulte. That is a useful ceiling for your thinking: the referral premium exists, but it is modest, and the authors argue firms should use a selective approach rather than paying a flat rate to everyone.

Here is a worked example with easy numbers. Suppose your average first order is $80 and your gross margin on it is 40 percent, or $32. If you pay a $20 credit to the referrer and a $20 credit to the friend, you have spent $40 in potential margin to acquire $32 of first-order margin. That only works if the referred customer comes back. If your data says a referred customer places 2.5 orders in the first year, the acquisition pays back, but slowly, and one fraudulent payout erases several honest ones.

Now apply the cap. A tiered structure that increases rewards after several verified referrals motivates genuine advocates, but it also hands a bigger prize to anyone running fake accounts. Impact's guidance is to cap rewards by value or quantity, and to move proven high-volume advocates into a separate segment with higher limits rather than raising the ceiling for everyone per Impact. Set the default cap at a number a normal customer could plausibly hit (say, five verified referrals a month) and treat anything above it as a manual review trigger.

If you sell infrequently at high value (furniture, mattresses, cars), a small percentage discount is nearly meaningless to the referrer, and a large one is a margin disaster. Referral Rock's advice for that case is to shift toward a fixed-value reward outside the product, because a $50 store voucher for a mattress purchase gives the referrer almost no reason to act per Referral Rock's program ideas. The fraud exposure there is lower anyway, because qualifying requires a genuine high-value purchase.

Pick the vesting moment before you write the reward copy

Timing is the single highest-leverage control you have. The question is: when does the reward become payable? There are four common answers, and they are not equally safe.

  • At link click. Worst option. You are paying for traffic, and click fraud is cheap.
  • At referred signup. Cheap to fake. A working email address is the entire cost.
  • At first paid order. Much better, because a payment method is now involved, but refunds and chargebacks can still unwind the sale after you have paid.
  • After the return window closes. Safest. The money has settled and the referred customer has kept the product.

Impact's guidance is explicit: if you have a return or refund period, make sure rewards are only paid out after it ends per Impact. Referral Factory's version adds a review step or delay before high-value payouts, long enough for refunds and chargebacks to surface before the reward is final per Referral Factory.

This matters more than it looks, because chargebacks are expensive in ways beyond the refund. Friendly fraud, where the cardholder made the purchase and later disputes it, now accounts for roughly 70 to 75 percent of chargebacks, and consumers file them partly because it is easier than asking the merchant for a refund per Flagright's chargeback analysis. A fraudster using a stolen card to qualify a referral can trigger a chargeback weeks later. If your reward already left the building, you absorb both losses.

Set the vesting date from your own policy, not a round number. If your return window is 30 days and your card processor disputes typically arrive within 60 to 120 days, a 30-day vesting period catches most refunds but not all chargebacks. A defensible default is the longer of your return window or your typical dispute lag, with manual review above a defined reward value.

Build the terms so clawbacks are enforceable

Most referral programs have terms nobody reads and everyone agrees to. That is fine for honest customers and useless against fraud unless the terms say three specific things:

  1. What counts as a valid referral. A new customer with no prior account and no prior purchase, whose first order is paid and kept past the return window.
  2. What counts as abuse. One person controlling multiple accounts, sharing signals with the referred account, or distributing codes on coupon and deal sites.
  3. What happens when abuse is found. Reward reversal, account suspension, and forfeiture of accrued value.

Impact's guidance is to state clearly that referral fraud leads to account cancellation, noting this is especially effective for SaaS, games, and marketplace businesses where customers have a real interest in keeping their account active per Impact. The threat has to be specific to be a deterrent: name the accounts affected, the rewards reversed, and whether the referred customer is also removed.

Clawback mechanics need a home in your systems, not just your legal page. Two workable patterns:

  • Hold and vest. No reward is issued until the vesting date passes. Simple, honest-friendly, and needs no clawback at all in most cases.
  • Issue and reverse. Issue at first paid order, then reverse if a refund, chargeback, or abuse finding arrives. Faster gratification, more reversal work.

Hold and vest is easier to explain and harder to game. If you use issue and reverse, keep a ledger that ties every reward to a specific order ID, so a reversal can be traced and applied without guesswork.

Detect duplicate accounts on the signals you can actually match

Detection is a data problem, and the good news is that the list of matchable signals is short. The most common fraud pattern is someone referring themselves with a second email to claim both sides of the reward, so watch for shared IP address, device, payment method, or shipping address across the referrer and referred account per Referral Factory.

Rivo's built-in checks give a concrete picture of what a mature rule set looks like: IP address comparison to cap referrals per household or network, self-referral blocking by email including plus-address variations like [email protected], shared phone number detection, checkout shipping address matching, cookie tracking to catch same-browser signups, and validation that the referred account is genuinely new with no prior purchase history per Rivo's fraud prevention documentation. Rivo also allows a threshold on shared networks, permitting a set number of referrals per week before blocking further ones from the same IP, which avoids punishing people in shared offices or campus housing.

A workable rule set, in order of how much fraud each catches per unit of honest-customer friction:

CheckFraud caughtHonest-customer frictionSuggested action
Email plus-address and exact matchSelf-referral with a second emailNoneBlock automatically
Existing customer check on referred emailExisting customers claiming to be newNoneBlock automatically
Shared phone numberDuplicate accountsLow (households may share)Flag, allow one per household
Shared payment method or shipping addressSelf-referral with a new emailLow to mediumFlag for review
Shared device or IPSame-person accountsMedium (offices, campuses)Threshold, then block
Velocity: many referrals in a short windowBots and code resellersLowCap, then review
Order kept past return windowChargeback and refund fraudLowHold reward until then

Two details earn their keep. First, phone and payment method are stronger signals than IP, because IP addresses are shared legitimately. Second, the velocity check is not really about fraud detection; it is about fraud economics. Hundreds of referrals from one account in a short window is not word of mouth, it is usually a bot or someone reselling codes per Referral Factory.

If you are matching these signals across systems, the joins get messy fast. A small model or embedding-based match on address and name variants can help, and running it through a single inference endpoint keeps the code simple. Quanta Inference exposes text and embedding models through one OpenAI-compatible key, which is enough to build a duplicate-account scorer without stitching together providers see the inference product.

Write the program rules as a short, testable checklist

Everything above collapses into a document your support team can apply without judgment calls. Use this as the skeleton:

  1. Eligibility. Referrer must be an existing customer in good standing. Referred person must have no prior account and no prior purchase.
  2. Reward. Defined per side, in a specific type (credit, discount, product), with a stated face value and expiry.
  3. Qualification. First paid order, above a stated minimum, paid with a non-disputed payment method.
  4. Vesting. Reward becomes payable after the return window closes and the typical dispute lag has passed.
  5. Caps. Default monthly and lifetime referral limits, with a named path to a higher tier through manual approval.
  6. Prohibited conduct. Multiple accounts, shared signals with a referred account, posting codes on coupon or deal sites, and any attempt to manufacture qualifying orders.
  7. Enforcement. Reward reversal, account suspension, forfeiture of accrued value, and removal of fraudulent referrals from all totals.
  8. Review triggers. Any referral above a value threshold, any account hitting the velocity cap, and any account flagged by duplicate detection.

Two notes on how these rules interact with the rest of your marketing. Referral program software exists mainly to track who referred whom and issue the right reward, and Salesforce's guide describes the core capabilities as easy submission, accurate tracking, and rewards for each verified referral per Salesforce's referral program guide. Your rules should live inside that system so the checks run at the moment of the event, not in a spreadsheet afterward. And keep the customer-facing explanation short: honest customers should be able to understand eligibility, qualification, and vesting in under a minute. The enforcement clauses can live in the linked terms.

If the program is one of several things you are building at once (the referral flow, the duplicate checks, the payout ledger), describing the whole thing to a builder and having it delivered is often faster than assembling it from plugins. That is the kind of build Quanta takes on with you via the main product.

FAQ

FAQ

Should the reward be cash or store credit?

Default to store credit or a non-cash perk unless your product is high-ticket and infrequent, where a fixed-value reward outside the product makes more sense. Cash is the most liquid reward and therefore the most attractive to fraudsters, and it is the hardest to reverse once paid. Credits cost you margin rather than cash and give the recipient a reason to buy again per Referral Rock.

When exactly should the reward pay out?

After the referred customer's first paid order has cleared and the return window has closed. Paying at click or signup is cheap to fake, and paying at first order still exposes you to refunds and chargebacks. Impact's guidance is to pay only after any return or refund period ends per Impact.

How large should the reward be?

Small enough that a fraudulent payout does not damage your margin, and large enough that a genuine customer notices. Work from your first-order gross margin and the number of orders a referred customer places in the first year. Paying two sides $20 each against $32 of first-order margin only works if the customer returns, so model the repeat rate before you set the number.

What checks stop self-referral?

Matching email (including plus-address variants), phone number, payment method, shipping address, and device or IP across the referrer and the referred account. Rivo's rule set also blocks referrals to emails that already have a purchase history or an account, and uses cookies to catch same-browser signups per Rivo. No single check is sufficient; stack them and act automatically on the cheapest ones.

Can I take a reward back after paying it?

Yes, if your terms say so clearly and you keep a ledger tying each reward to an order. State that abuse leads to reversal, account suspension, and forfeiture of accrued value, and name the actions in the terms rather than describing them vaguely. Impact notes that the threat of losing account access is a strong deterrent for SaaS, game, and marketplace customers, provided the consequence is specific per Impact.

Sources

Sources

  1. Referral Abuse: Common Types & How to Prevent Them
  2. How do I prevent referral fraud?
  3. How to Choose the Best Referral Rewards 24+ Examples
  4. What Is A Double Sided Referral Program? With Examples
  5. Design a Fraud-Proof Referral Program | I'm a Brand
  6. PDF Referral Programs and Customer Value - Wharton Faculty Platform
  7. 22 Customer Referral Program Ideas That Actually Work
  8. Chargeback Economics 2025 for Payment Processors
  9. Referrals fraud prevention tools
  10. How to Build an Effective Referral Program - Salesforce
About the author

About the author

Antonio Evans
Antonio Evans

Antonio Evans is the founder of Quanta Intelligence and a fractional CTO who builds HIPAA-ready AI systems for health and life-science companies. Before that he was technical co-founder of FriendsEAT for twenty years, CEO of Socialdraft, and a data engineer at IBM. Antonio lives with his dog Santino in Lisbon, Portugal.

All articles